
Shareholder Protection Insurance Guide
Have you considered the consequences for your company if a substantial shareholder suffered a severe injury, illness, or death?
Could the other shareholders buy the shareholding? If not, what would the consequences be?
This detailed guide will explain how shareholder protection insurance works and why it can provide certainty for your business.
The Smartest Way To Protect Your Business, Shareholders And Employees. Get A Free Shareholder Protection Quote today.

The tables below aim to provide a concise overview of Shareholder Protection Insurance. The rest of our guide explains the core fundamentals in more detail.
Insurance Hero has years of experience protecting businesses. We are confident we can find the right coverage for your business’s unique requirements.
Overview of Shareholder Protection Insurance:
| Feature | Description |
|---|---|
| Definition | A type of insurance that provides the funds for remaining shareholders to buy the shares of a deceased or critically ill shareholder, ensuring business continuity. |
| Purpose | To prevent shares from falling into unwanted hands and ensure the deceased’s family receives fair compensation. |
| Benefits | Maintains control within the remaining shareholders, provides financial stability, and minimises disruption. |
Types of Agreements in Shareholder Protection:
| Agreement Type | Description |
|---|---|
| Cross-Option Agreement | Allows the surviving shareholders or the deceased’s estate to initiate the buy-sell process. |
| Double Option Agreement | Similar to Cross-Option but specifically designed for life cover scenarios. |
| Single Option Agreement | Used for critical illness situations, providing flexibility in share purchase. |
Tax Considerations for Shareholder Protection Insurance:
| Aspect | Description |
|---|---|
| Income Tax | Generally, there is no income tax liability on the proceeds from the policy. |
| Capital Gains Tax (CGT) | It may apply if shares are sold for more than their purchase price. |
| Inheritance Tax (IHT) | Properly structured policies can avoid IHT, especially with business property relief. |
Factors Affecting Cost of Shareholder Protection Insurance:
| Factor | Impact |
|---|---|
| Age of Shareholder | Older shareholders typically incur higher premiums. |
| Health Status | Pre-existing conditions can increase premiums. |
| Lifestyle | High-risk lifestyles may lead to higher costs. |
| Coverage Amount | The level of cover required directly influences the premium. |
Choosing a Provider for Shareholder Protection Insurance:
| Consideration | Description |
|---|---|
| Provider Reputation | Established insurers with a track record of reliability are preferred. |
| Policy Flexibility | Policies that offer customisation to fit specific business needs. |
| Cost-Effectiveness | Competitive premiums with comprehensive coverage. |
| Advisory Services | Providers or brokers offering expert advice to tailor policies accurately. |
What Is Shareholder Protection Insurance?
Shareholder protection provides business shareholders with the funds to buy out one another’s shares if one becomes unable to work again due to death, injury, or illness.
It is a life insurance-based protection that can include other elements, such as terminal illness and critical illness coverage.
How Does Shareholder Insurance Work?
Shareholder protection pays out a financial amount if the covered shareholder dies or is diagnosed with a critical or terminal illness. The lump sum enables the other shareholders to buy the deceased shareholder’s shares.
Calculations use various factors to determine the required premium level. An insurer will consider the policyholder’s age, any underlying medical problems, and whether they lead a higher-risk lifestyle.
Does Our Business Need Shareholder Protection?
To decide whether your business needs shareholder protection in place, consider the following two points:
- Should the key shareholder die, will the remaining business owners be able to retain control of the business?
- Does your business have a shareholder agreement that covers what happens if a shareholder becomes critically ill or dies?
What Are the Advantages of Shareholder Protection?
When a shareholder dies without deciding what to do with their shareholding, the company shares typically pass to the beneficiaries of their estate, who then have to make decisions.
- It includes either taking the proceeds from the company’s shares or selling the shares.
- Taking over the shareholder’s position within the company
With shareholder protection insurance, the family or a family member isn’t forced to decide because they receive a lump-sum payout for their shareholding, distributed among the other shareholders.
Protect Your Business For Less – Compare & Save – Policies From UK’s Leading Insurers
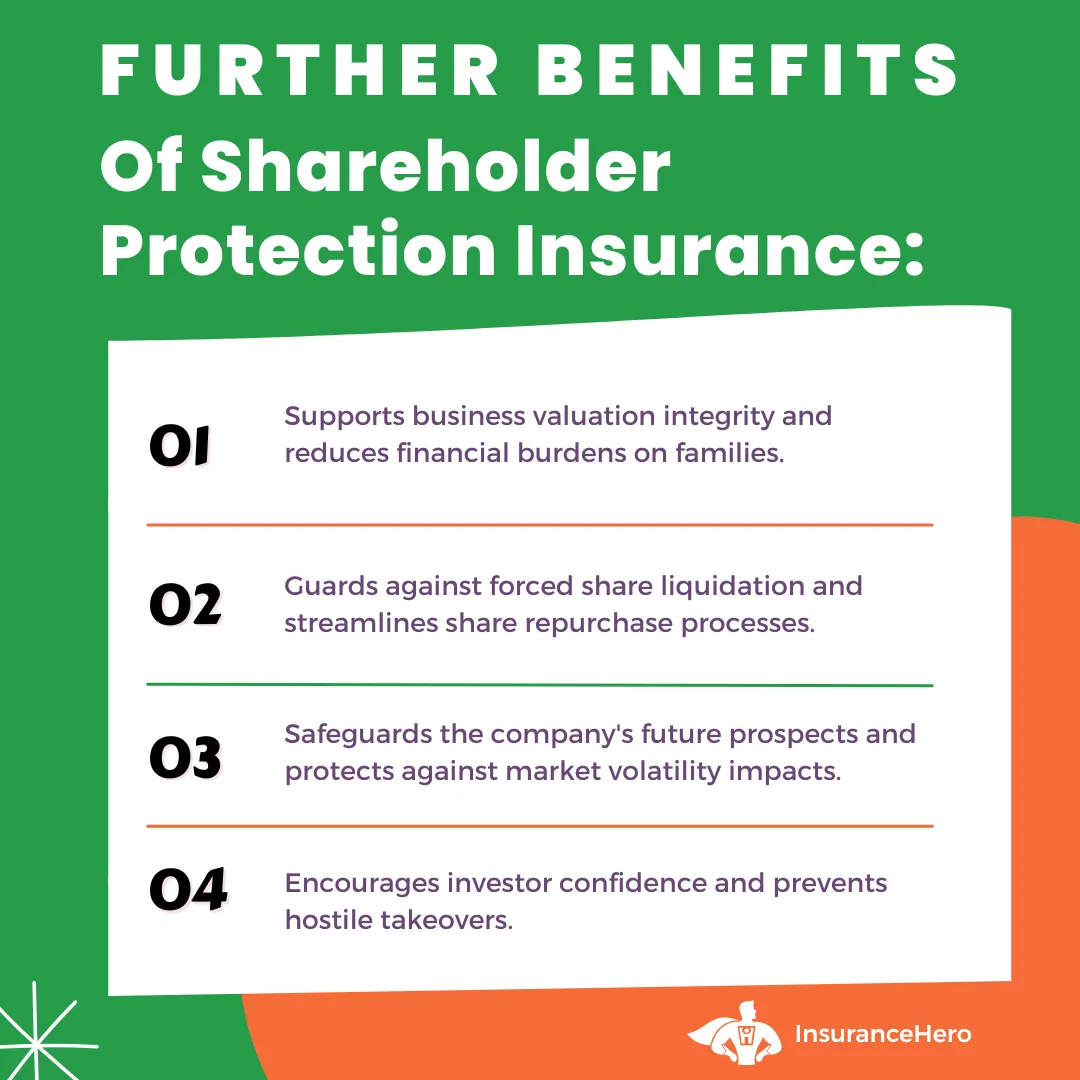
With the cover in place, it avoids the following potential problems:
- The remaining shareholders will not acquire a sleeping shareholder who adds no value to the business.
- Surviving shareholders may lose control of the company.
- The family is unhappy as they have no control over the business profits they require for income.
How Do I Set Up Protection?
Businesses must have the correct valuation to set up shareholder insurance, which an adviser specialising in this cover must undertake.
Valuing companies can be complicated, as every firm is different and its sector matters. Key considerations for valuing the business include profit and cash flow analysis.
Insurance Hero has extensive experience in providing share purchase protection. Our professional team can help you get a quote tailored to your business’s needs. Contact us today at 0203 129 8866.
How much is shareholder protection insurance?
The cost of shareholder protection insurance can vary, as many factors affect quotes, premium levels, and the sum assured.
Considerations for insuring a shareholder include:
- Do they have a high-risk lifestyle, such as participating in extreme sports?
- Do they have any underlying medical conditions?
- How old is the shareholder?
- Are they a smoker or a non-smoker?
- What policy term is required?
- What level of cover is required?
- Are critical illness and terminal illness a requirement?
Let us consider the following examples to provide an idea of cost:
For a 10-year shareholder protection policy, insuring a 34-year-old non-smoker with no underlying medical problems will cost around £7 a month. For a 53-year-old with the same lifestyle criteria, the monthly cost rises to approximately £26.
If you add critical illness cover to the life policy, the cost rises to £32 a month for the 34-year-old and £155 a month for a 53-year-old shareholder.
How Is Our Business Valued for Shareholder Insurance?
Valuing a business for shareholder protection can take time, as different considerations come into play. Depending on the complexity of the company’s requirements, a specialist insurance advisor and, if necessary, a tax expert will need to review the matter.
Insurance Hero can help at each step and has helped hundreds of UK businesses over the years.
At a minimum, the following need to be looked at:
- A full cash flow analysis of the business
- Calculating all cash deposits and assets as a multiple of net profit
- A detailed analysis of the business’s profits and how they are changing over time
For further details on shareholder protection insurance and protecting your business, contact Insurance Hero today. Our experienced team of professionals can provide an accurate quote that aligns with your company’s needs.
Shareholder Protection Insurance Tax Treatment. Is Shareholder Protection Insurance Tax Deductible?
Shareholder protection insurance is a more complex type of cover. A valuation requires a specialist adviser, and you must consider key tax implications before implementing a shareholder protection insurance policy.
Three methods exist for purchasing shareholder protection, and each has a specific tax position in HMRC’s eyes.
Taxation Methods:
- Life of Another: Each shareholder pays for the insurance from post-tax income, usually with no tax implications for premiums or payouts. However, because policy management is complex, it is practical for only a limited number of shareholders.
- Company Share Purchase: The company insures each shareholder receiving benefits to buy back shares without the premiums being deductible as a business expense due to not meeting the ‘wholly and exclusively for the purposes of trade’rule. A cross-option agreement is necessary to avoid future tax complications.
- Own Life Policy Under Business Trust: Shareholders insure their own lives and place policies in a business trust for fellow shareholders. If the company pays, premiums may be deductible as a business expense, but shareholders face P11D or benefit-in-kind taxes. Individual shareholder payments come from post-tax income, typically without further tax implications.
It is vital to get professional advice before putting in place the correct type of policy for your business, including its impact for Inheritance Tax purposes.
Further Tax-Related Considerations
What about Premium equalisation?
Equalising premiums ensures shareholder protection policies are set up commercially and that the cost of cover is divided equally among all the business’s shareholders.
In most cases, each shareholder’s premium will correlate with the level of protection needed to cover their shareholding percentage in the business.
For HMRC, premiums may need to be equalised in some instances to prevent unequal premiums from being viewed as a transfer of wealth, with shareholders paying the highest premiums subsidising minority shareholders paying the lowest premiums.
Cross-option agreement
Also called a double option agreement, it is a legal arrangement between the insured shareholder’s estate and the surviving shareholders. It sets out a schedule for who will purchase the shares and at what price.
The arrangement provides certainty by setting out the percentage allocation for each individual shareholder and the amount they will receive from the estate.
Shareholder protection insurance benefit in kind
Benefits in kind are remuneration a business provides to a shareholder or employee above their salary. It can include fringe perks such as a company car, private medical insurance, or even food vouchers to spend in a local store.
Shareholder business protection is complex insurance, and how you set it up dictates whether HMRC classifies it as a benefit-in-kind, which affects tax. Getting guidance from a specialist such as Insurance Hero is vital before implementing any policy.
Other Types of Insurance Protection for Your Business
Keyman Insurance
Keyman insurance pays a lump sum to a company if a key member of staff dies. If critical illness cover is part of a policy, it provides protection if the insured is unable to return to work due to illness or injury, not just death.
The payout from keyman cover can be used for several purposes, including creating a buffer against any fall in profits following the loss of a staff member or the cost of recruiting and training a replacement employee.
Business Loan Protection Insurance
If a business owner dies or becomes unable to work, the lender may recall corporate debt tied to a business founder or shareholders if the loan is linked to personal finances.
To protect against this, business loan insurance can match the outstanding debt with a cash payout to repay it if the insured dies.
Many corporate lenders insist that a business take out loan protection insurance before funding is in place.
Relevant Life Insurance
Relevant life insurance is financial protection beyond a salary that a company offers its employees to provide a financial cushion for their loved ones should they pass away in service.
The cover is written into a trust, and a lump sum is paid to the employee’s dependents. The lump sum can be used to pay off outstanding debts or to help the family maintain a lifestyle and live comfortably day to day.
For an employer. Providing a product like relevant life cover shows care beyond simply paying a salary.
Business Partnership Protection Insurance
If you are in a professional partnership with fellow partners, and one partner passes away or cannot return to work, issues like retaining control and keeping the partnership going may arise.
Business partnership protection insurance is a product tailored to the partnership business model. It provides the remaining partners with a payout sufficient to maintain a controlling interest and buy out the absent partner’s interest in the partnership.
Summary
Shareholder protection can increase your business’s certainty if something happens to one of your fellow shareholders. Importantly, it provides the other shareholders with the financial means to retain control of the company.
If you want peace of mind that your business will not fail because of a fellow shareholder’s death or illness, consider shareholder protection insurance.
Steve Case is a seasoned professional in the UK financial services industry, with over twenty years of experience. At Insurance Hero, Steve is known for simplifying complex insurance topics, making them accessible to a broad audience. His focus on clear, practical advice and customer service excellence has established him as a respected leader in the field.
