
Cancer Life Insurance And Critical Illness Quotes


When a medical tragedy strikes, knowing there is financial support for you and your family can bring a lot of relief to everyone involved.
Cancer is not an easy topic to discuss. Still, the statistics surrounding this devastating illness make cancer insurance worth serious consideration when considering a life insurance policy and critical illness coverage.
Adding cancer life insurance to your insurance coverage portfolio can help protect you and your family’s financial future and aid with the high cost of medical bills associated with this illness.
This protection lets the policyholder and their family focus on recovery rather than financial stress.
Cancer Life Insurance In Summary:
Securing life insurance with a cancer diagnosis is a financially wise decision to protect your loved ones during uncertain times.
Insurance Hero can help you find the most comprehensive and cost-effective policies.
Here’s why it’s worth considering:
- Comprehensive Coverage: Even with a cancer diagnosis or family history, options like guaranteed life insurance and personal accident insurance can provide immediate financial protection for your family, with some policies not requiring medical questions.
- Cost-effective Peace of Mind: Policies tailored to cancer survivors’ financial capabilities dispel the misconception that life insurance is unaffordable after cancer, making it an accessible support option.
- Expert Guidance Available: Specialised cancer life insurance advisors offer invaluable insights, helping you navigate the complexities of insurance options and secure the best rates from compassionate insurers who understand your journey.
- Long-term Financial Security: As you move through recovery, life insurance becomes more attainable and affordable. It ensures that your loved ones are financially safeguarded long-term, making it a prudent step in managing life’s uncertainties.
Many cancer insurance options are available, and Insurance Hero is here to help you find the policy that best fits your needs.
Compare Life Insurance Quotes For Cancer Patients And Those In Remission
Important Information Regarding Cancer Life Insurance
Does life insurance cover cancer? Generally, critical illness policies that include cancer life insurance will cover individuals up to age 70 or 75, while selected plans will even cover individuals up to age 85.
When thinking about purchasing this kind of insurance, it is important to remember that almost 10 per cent of all new cancer diagnoses occur before the age of 50, and almost 55 per cent of new cases occur before the age of 75.
Researching and purchasing this policy early on may be a wise decision, given these statistics.
Premiums for cancer life insurance generally increase over time, so buying this coverage early can help lock in lower rates.
If you already carry cancer insurance, also review the types and stages of cancer it covers.
Critical illness and cancer coverage can change with ever-improving advances in screening and treating this disease.
Some policies may become outdated as this disease is diagnosed and treated at much earlier stages than before.
What Conditions are Covered Under Cancer Life Insurance?
The two most commonly diagnosed forms of cancer are prostate cancer and breast cancer. These two forms of cancer are generally covered under most cancer insurance and critical illness cover policies.
Most policies also offer additional coverage for the earlier stages of these particular diseases.
Breast cancer accounts for approximately 30 per cent of all cancer diagnoses in women in the United Kingdom, while prostate cancer accounts for approximately 25 per cent of all cancer diagnoses in men.
Recent changes to cancer insurance now cover additional procedures to reflect advances in medical screening and diagnosis.
Previously, coverage for surgeries for women was limited to mastectomies, whereas recent coverage now supports a wider range of procedures.
Also, cancer life insurance issued by several providers now covers lower-grade prostate cancer for men. These coverage changes help insurers keep pace with the latest advances in medicine. Most types of skin cancers are also covered.
Not All Policies Are Created Equal
Although cancer is considered a core critical illness under most critical illness cover policies, not every policy covers less advanced forms of this disease.
Because of this, thoroughly research any cancer insurance policy and ensure it meets your coverage needs.
The Association of British Insurers, or ABI, defines cancer as “any malignant tumour diagnosed as positive and characterised by the growth of malignant cells and tissue invasion.”
This definition applies to illnesses such as sarcoma, leukaemia, and lymphoma.
Because of how the ABI defines cancer, some policies may not include coverage for conditions such as pre-malignant tumours, non-invasive tissue, borderline malignancy, low-grade prostate cancer, early stages of breast cancer and several other circumstances.
Review any cancer insurance policy and fully understand which diagnoses may not be covered.
A cancer diagnosis can be a devastating shock to any individual and his or her loved ones.
Although no amount of planning can prepare a family for dealing with this terrible disease, purchasing critical illness cover with cancer insurance can help those, including women, who are suffering from cancer. As a result, their families have one less thing to worry about.
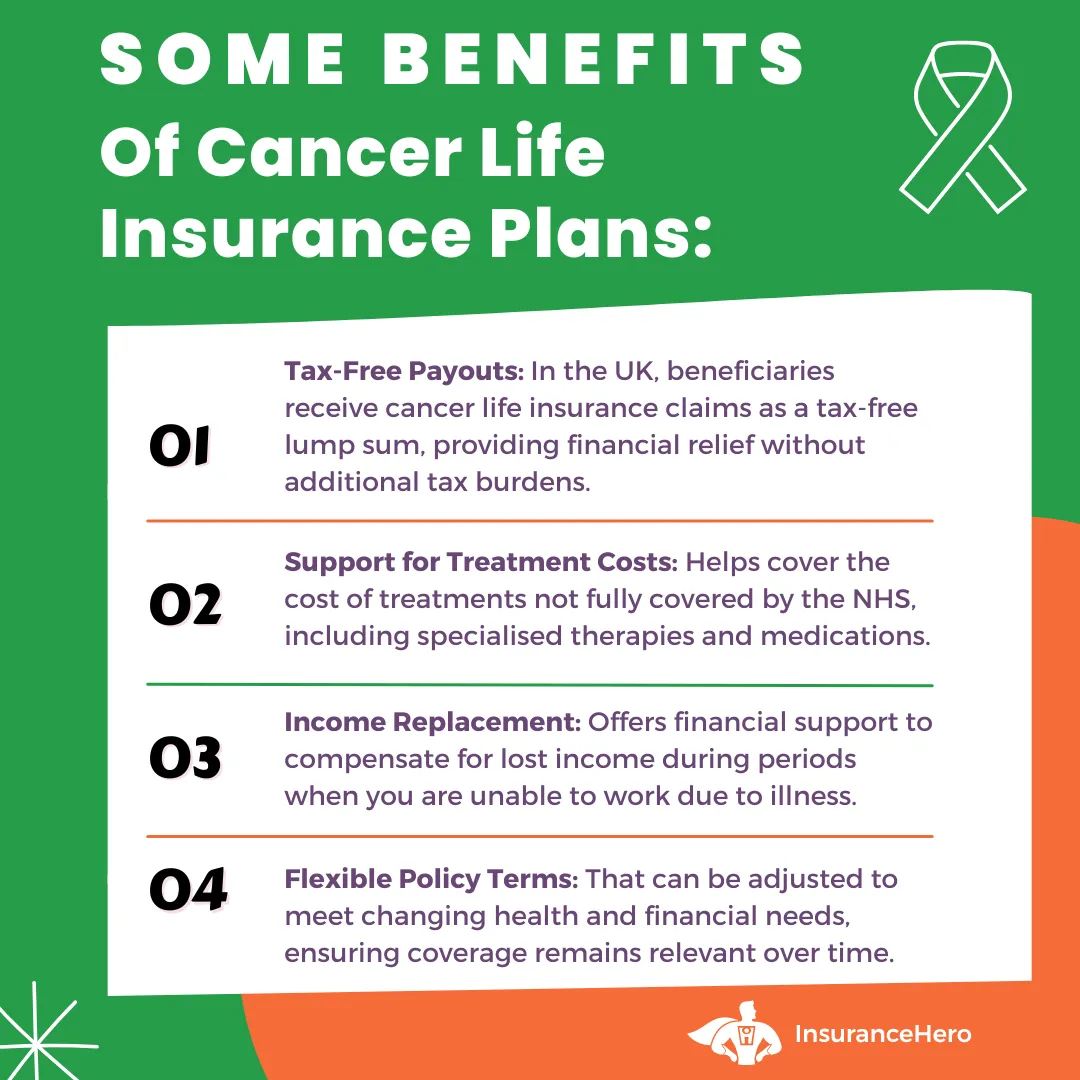
Cancer life insurance can help manage high medical expenses, and choosing a policy that fits your needs can further ease a policyholder’s mind.
Life insurance with pre-existing medical conditions is also available through the Insurance Hero team.
What Happens With Life Insurance If You Are Diagnosed With Cancer?
If you are diagnosed with cancer, you should first check if your life insurance policy covers it. If you have critical illness coverage, you can receive funds to cover therapy, needed equipment, or living expenses while you cannot work (only if your diagnosis is included in your policy).
You can also count on a payout when diagnosed with a terminal illness. If you have terminal illness cover and have received a diagnosis with a life expectancy of fewer than 12 months, you can claim this.
However, it’s essential to know that specific requirements must be met. For example, you must pay your premiums throughout the policy term. If you have any inconsistencies, you might not be eligible for the payout.
If you receive a cancer diagnosis during the life insurance policy term, check whether you are insured and what requirements you must meet to benefit from the coverage.
Cancer patients can benefit from coverage, as life insurance providers are obligated to fulfil the terms of the policy, even if they get ill during its term.
The only exception is individuals who lie about their medical history during the life insurance application process.
Can I Get Life Insurance 5 Years After Cancer?
Many insurance providers can offer you a traditional life cover if you’ve been in remission for five years. The longer you’ve been in remission, the easier it should be for you to qualify for various life insurance policies.
But it’s not the only factor a life insurance company will consider when processing your application.
Other important aspects that will determine whether or not you can purchase a cover are:
- The type of cancer you had,
- The severity of the illness,
- How long you received treatment.
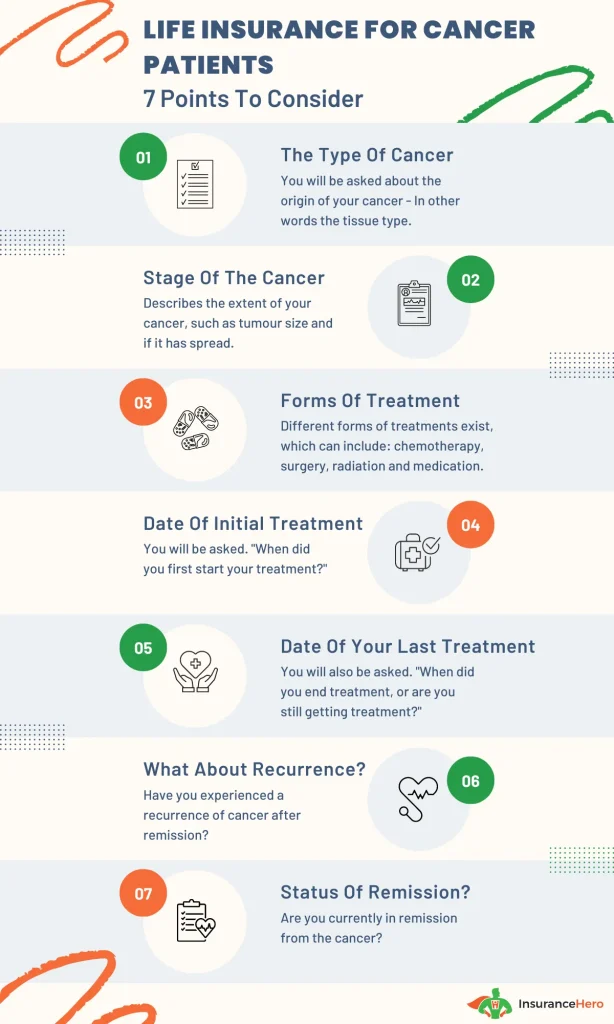
We will discuss all of these during your application when the insurer asks about your medical history.
Additionally, you may be asked about the recurrence of the disease, your family history of the disease, and whether the cancer was surgically removed or not.
Your age, history of other illnesses and pre-existing medical conditions, and additional risk factors, like whether or not you smoke, will also influence the insurance company’s decision.
Generally, you have to be at least one year into remission to qualify for most life insurance policies, and still, you may get rejected, depending on the type of cancer you had.
It’s also expected that your life insurance premiums will be higher.
Moreover, many life insurance providers won’t offer their policies to cancer survivors with less than three years of remission.
Contact us if you’re unsure whether you can apply for life insurance as a cancer survivor. At Insurance Hero, we can help you find the best cancer insurance in the UK.
| Key Points | Our Explanation |
|---|---|
| Importance of Cancer Life Insurance | Cancer insurance provides financial support during a medical tragedy, helping families focus on recovery rather than financial issues. |
| Cancer Statistics | Almost 10% of all new cancer diagnoses occur before age 50, and 55% before age 75. Early insurance can lock in lower rates. |
| Types of Cancers Covered | Most policies cover prostate and breast cancer, with recent changes reflecting advances in medical screening and diagnosis. |
| Policy Variations | Not all policies cover less advanced forms of cancer. It’s crucial to understand which diagnoses are or aren’t covered. |
| Impact of Cancer Diagnosis on Existing Life Insurance | Life insurance provides peace of mind during challenging times. Even with higher premiums, securing a policy can benefit the family’s future. |
| Life Insurance Post-Cancer | Many providers offer traditional life cover to individuals in remission for five years. Factors considered include type of cancer, severity, treatment duration, and other health conditions. |
| Types of Policies for Cancer Patients | Options include Terminal Illness Cover, Cancer Critical Illness Cover, Term Life Insurance, and Over 50s Life Insurance Policy. |
| Value of Cancer Patient Life Insurance | Life insurance provides peace of mind during challenging times. Even with higher premiums, securing a policy can be beneficial for the family’s future. |
| Recommendation | It’s advised to secure critical illness or terminal illness coverage early. Insurance Hero can assist in finding the best policy for cancer patients. |
What should I do if I’ve been declined life insurance because of cancer in the past?
Suppose your application for life insurance was previously rejected due to a cancer diagnosis.
In that case, there are several steps you can take to enhance your chances of obtaining coverage in the future:
- Wait the Appropriate Time: Insurance companies often require a waiting period after cancer treatment before considering an applicant for coverage. This typically lasts about two years, but the duration varies by insurer and the specific disease and treatment. Make sure you’ve passed this threshold before applying again.
- Select the Right Insurer: Some insurers are more accommodating than others when it comes to insuring individuals with pre-existing conditions, including cancer. Research or consult a specialist, such as Insurance Hero, who understands the life insurance landscape for cancer survivors and can guide you to companies with more lenient policies on past cancer diagnoses.
- Don’t Disclose Previous Declines: When applying for new coverage, remember that insurers typically do not have access to information about your previous applications unless you disclose it. Unless specifically asked, there’s no need to mention that you were previously declined.
- Stay Persistent: Do not be discouraged by a past rejection. Insurance policies and their criteria can change, and your health circumstances might evolve, making you a more favourable candidate.
By taking these careful and informed steps, you can significantly increase your chances of successfully obtaining life insurance even with a history of cancer.
What types of cancer does Cancer Research UK list?
Cancer Research UK details a comprehensive list of cancer types, organised alphabetically. This includes various forms of leukaemia, such as Acute lymphoblastic and Acute myeloid, and tumours affecting different organs like adrenal glands and anal cancer.
Disorders like Barrett’s Oesophagus and Basal cell carcinoma are also mentioned, along with common cancers like bladder, breast, and bone cancers.
The list also includes cancers that have metastasised to other parts of the body, such as the bone, brain, liver, and lung.
Various specific cancers like cervical, colorectal, and those affecting children are also referenced, along with rarer types such as ear, endometrial, and eye cancer.
The text covers gastrointestinal cancers extensively, including those affecting the gallbladder, gastrointestinal system, and gastrointestinal junction.
The text also highlights other types, such as Hodgkin lymphoma, head and neck cancers, specific sarcomas (e.g., Kaposi’s), and conditions such as hairy cell leukaemia.
The list includes cancers of the kidney, larynx, liver, and lung, including primary and neuroendocrine tumours.
The skin cancers listed include melanoma and Merkel cell carcinoma, as well as Mesothelioma and various gynaecological cancers, such as ovarian and uterine cancers.
Pancreatic, penile, and prostate cancers are also discussed, along with rare types such as retinoblastoma and, rarer still, tumours of the adrenal glands and thymus glands.
Cancers with unknown primary origins and other significant intestine-related cancers like those of the salivary glands, stomach, and thyroid are also included.
The categorisation ends with specific cancer types affecting the testes, vagina, vulva, and Wilms’ tumour, among others.
This wide-ranging list reflects the diverse cancer types recognised by Cancer Research UK, including cancers affecting virtually every body part.
Can I Get Life Insurance If I Have Cancer?
In most cases, buying life insurance while battling cancer might be difficult. That is why it’s crucial to consider this coverage before getting ill.
If you want to secure your future and take care of your loved ones in the event of getting diagnosed with cancer, here are the best types of policies you can consider.
Terminal Illness Cover
Terminal illness cover pays out if you are diagnosed with a terminal illness. This cancer patient’s life insurance can help you cover the costs of therapy and required modifications to your home.
You may claim this policy only when your illness is terminal, meaning there are no treatment methods to result in recovery, and your life expectancy is less than 12 months.
Your family can’t ask for a payout from this policy after your death. But if you receive the money and live to the end of the term, you’re not obligated to return it. After claiming the payout, no further claims can be made.
Some life insurance policies offer a terminal illness benefit. If you are expected to live less than a year, you can receive the full insurance payout immediately.
Cancer Critical Illness Cover
Critical illness cover is meant to protect you if you are diagnosed with the illness covered by the policy. You will receive a lump sum you can use to cover living expenses.
At the same time, you may be unable to work and face the costs of rehabilitation, needed equipment, mortgages, or other financial obligations.
This policy aims to help you get back on your feet when you can’t work and to provide financial support for you and your family.
Cancer critical illness cover may be a valuable policy if you want to protect yourself and your family if you are diagnosed with this serious illness.
Term Life Insurance
Term life insurance is one of the most popular life insurance options. There are three main types of term life insurance.
Level-term insurance – This pays out a fixed amount to the policy beneficiaries after your death. The payout is fixed at the start of the policy term and does not change over time.
Decreasing term insurance – For this life cover, the payout your loved ones will receive decreases over time.
This term policy is often taken alongside substantial financial obligations, such as mortgages or your children’s tuition at schools and universities.
Increasing term insurance – This type of life insurance pays out after your death, and the sum your family receives increases over time. Often, increasing term insurance offers a payout that grows in line with inflation.
Over 50s Life Insurance Policy
Over-50s life cover suits individuals over 50 who want to secure their loved one’s future. The payout from this policy can be used to cover funeral costs and as an inheritance for your family.
Getting diagnosed with cancer is difficult enough, but with this cover, you can take care of your family after your death.
Is It Worth It To Have Cancer Patient Life Insurance?
Think of your future, whether you are healthy or have just been diagnosed with cancer. Good life insurance can give you peace of mind during one of life’s most challenging moments.
Even if you’re already ill, you can find an insurance provider that offers coverage. You can expect higher premiums and lower coverage amounts, but it’s still worth exploring, as it can help protect your family in the event of death. We offer comprehensive life insurance quotes for cancer patients.
Not every policy requires a medical examination, either. You can purchase over-50s life insurance and plan your funeral ahead of time.
Please don’t wait until it’s too late; secure critical illness or terminal illness coverage now. Explore your life insurance options after cancer.
Find the best cancer patient life insurance policy with Insurance Hero.
External resources on life insurance that covers cancer:
- https://www.cancerresearchuk.org/about-cancer/coping/practically/money/medical-insurance
- https://commonslibrary.parliament.uk/research-briefings/sn06887
- https://www.macmillan.org.uk/cancer-information-and-support/impacts-of-cancer/insurance-and-cancer
Steve Case is a seasoned professional in the UK financial services and insurance industry, with over twenty years of experience. At Insurance Hero, Steve is known for his ability to simplify complex insurance topics, making them accessible to a broad audience. His focus on clear, practical advice and customer service excellence has established him as a respected leader in the field.
