
Business Loan Protection Insurance 2026 Guide


Do you own a business? Are you worried about the business’s continuity, particularly its ability to repay any company overdraft or commercial loan if something happens to you or a key team member?
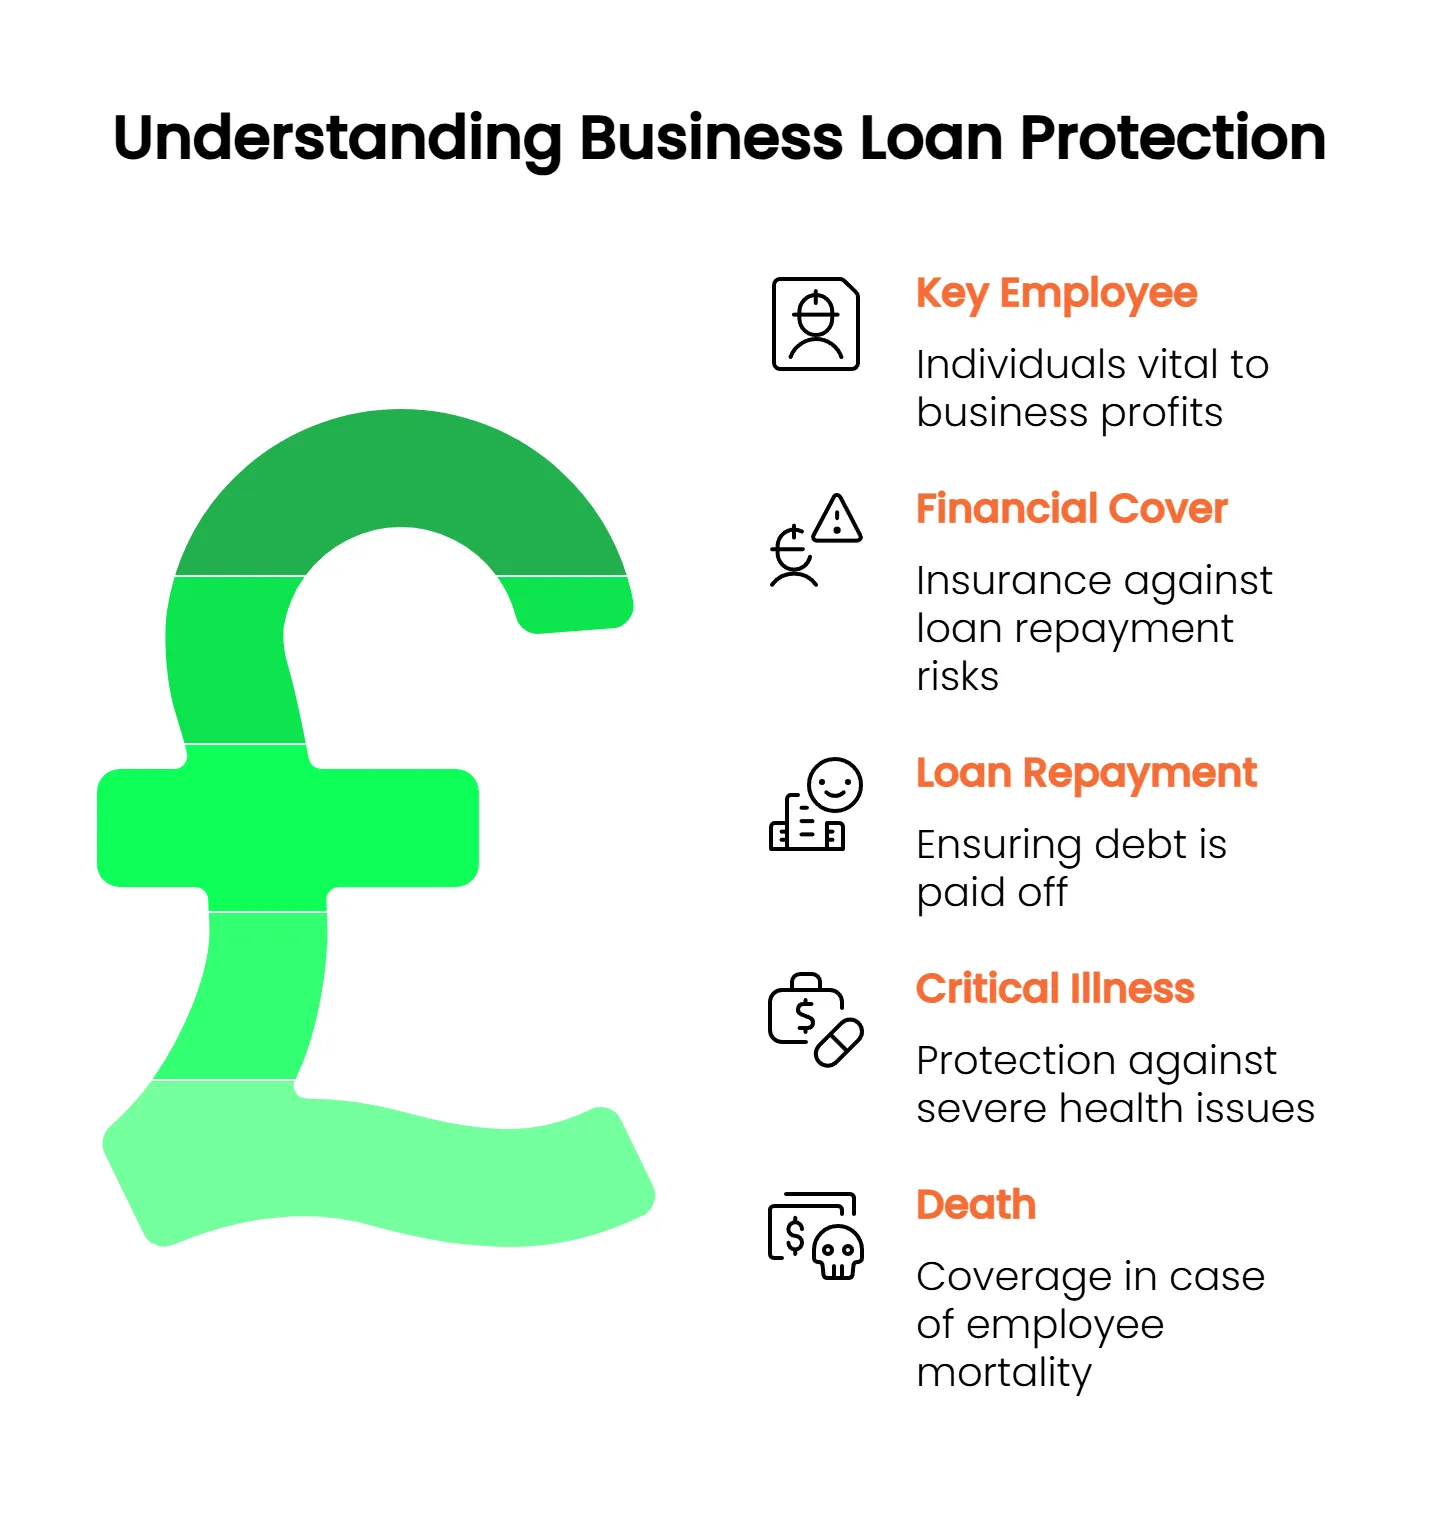
Did you know that business loan protection insurance is designed to repay any outstanding business debts or loans should you or an important employee die or not work due to a critical illness diagnosis?
This guide explains how it works and why businesses and startups should consider it.
Compare The Top 10 UK Insurers. Protect Your Business For Less – Compare & Save

These summary tables provide a concise overview of Business Loan Protection Insurance tailored to the UK market
Coverage Options
| Type | Description |
|---|---|
| Level Cover | The insurance coverage amount remains unchanged throughout the policy term and is suitable for interest-only loans. |
| Decreasing Cover | The cover amount decreases over time and aligns with the outstanding loan balance, and is recommended for capital and interest loans. |
Policy Considerations
| Consideration | Description |
|---|---|
| Tax Treatment | Premiums are not typically tax-deductible as a business expense, but the payout is usually tax-free. |
| Trust Ownership | Policies can be written in trust to ensure the payout is used to repay the loan directly, avoiding probate delays. |
Additional Benefits and Features
| Feature | Description |
|---|---|
| Critical Illness Cover | An optional addition to cover the diagnosis of specified serious illnesses. |
| Flexible Premiums | Options to choose between guaranteed or reviewable premiums. |
Market Considerations
| Subject | Detail |
|---|---|
| Underwriting Process | It may vary by insurer, with some offering ‘fast track’ processes for smaller loan amounts. |
| Insurance Providers | A range of insurers offer tailored products for different business sizes and sectors. |
What Is Business Loan Protection Insurance?
When a business owner or company director dies or becomes disabled to the point that continuing to work is no longer an option, corporate lenders may exercise their right to recall any outstanding debt related to the owner’s finances.
This scenario may put the business’s future, including its staff, at risk.
Like a life insurance policy, business loan protection pays out the value of the debts in return for a regular monthly premium tied to the size of the outstanding debt, allowing the business to repay any corporate loans, mortgages, or overdrafts.
Life cover can also repay loans made to the company by business owners or directors, as well as by external creditors.
Because some business loans may involve personal liability, this insurance can protect individual shareholders from losses.
Does Our Company Need Corporate Loan Insurance?
Protecting a business from outstanding financial obligations is not legally required. However, many corporate lenders will insist that loan insurance is in place so they can repay loans in the event of an incident.
If a director or shareholder is personally responsible for repaying a business loan, their death or incapacitation can cause the creditor to call in the full amount owed immediately.
A business without protection may be declared unviable or insolvent if a director or shareholder dies and the loan cannot be repaid.
Get Over £200k Of Loan Insurance Cover From £7.60 Per Month- Secure A Free Quote Below
How Much Cover Does Your Business Need?
The required coverage level should match the outstanding loan balance, known as the sum assured.
The lump sum paid to creditors if the owner or business partner dies will be reflected in the monthly or annual premium paid throughout the fixed-term policy.
How Much Will A Business Loan Protection Policy Cost?
The cost of taking out corporate loan protection depends on several factors taken into consideration by the insurer, including the following:
- What is the health of the person to be insured? Do they have any underlying medical conditions?
- Do they have a healthy lifestyle, exercise, and do not drink excessively or smoke?
- How old are they at the start of the policy?
- Is their job considered risky, or is it low risk?
For Example:
A 36-year-old business owner applying for a £140,000 business loan over a fixed term of 10 years with decreasing cover pays around £7 a month. For a 50-year-old, implementing the same policy will cost around £25 a month.
Insurance Hero is an independent broker who can provide a competitive quote closely aligned with your and your business’s needs. Contact our sales team today on 0203 129 88 66 for a fast and free quote.
Is business loan protection tax-deductible?
HMRC does not consider any payout from a business loan policy as benefiting a business, as any payout money goes directly to creditors.
Instead, HMRC treats premiums as part of the finance raised. This means that premiums are not considered tax-deductible business expenses.
Only the payout is usually tax-free, as the ultimate beneficiary of any payment is the creditors, not the business itself.
How about writing the Policy into the trust?
If a payout from a business loan policy is requested, the payout must go directly to creditors to settle any outstanding obligations.
If you write a policy into a trust, it adds a layer of complexity, as a trust is a separate legal entity from the underlying business. Putting a policy into a trust would only add unnecessary complexity when the goal is to pay lenders and settle debt.
Further Benefits Of Insurance for Loan Cover
As well as a financial payout when you most need it, a comprehensive business loan cover should also include the following key features:
- Sessions with a physiotherapist or an acupuncture professional
- Stress-related advice and counselling through a dedicated helpline
- Full 24/7 access to a GP by phone or video consultation
- An ability to increase or decrease the level of cover
- Switching the frequency of premiums between monthly and annual payments
- Reducing or extending the cover period
- Removing the insured person from a policy
Increasing or Decreasing Cover
Depending on the circumstances, increasing or decreasing the level of cover can be a helpful option.
Increasing cover
Under this cover, premiums and the sum assured will increase in line with the UK Government’s Consumer Price Index (CPI).
This benchmark indicates changes in the cost of living and policy premiums; as cover increases, premiums rise accordingly.
Decreasing cover
Premiums and the sum assured decrease over the policy’s fixed term. Decreasing cover is often associated with a commercial mortgage, where the borrowing amount decreases over the life of the loan, so the cover level must also decrease.
Level Cover
The level of insurance cover remains unchanged throughout the fixed-term policy.
What about Critical Illness?
Most providers offer the option to include critical illness coverage as part of their overall business loan insurance products.
It may be available as an option or added at no extra cost. Some insurers also refer to critical illness coverage as disability insurance, so it helps to understand the different terminology.
Critical illness is essential, as death is not always the outcome that will stop business owners from being able to run a business.
Critical illness covers the diagnosis of a disease where the insured will not be able to work, with a payment forthcoming should the person survive 14 days from diagnosis.
Critical illness can include qualifying diseases, including, but not limited to, the following:
- Kidney failure
- Liver failure
- Structural heart surgery
- Multiple sclerosis
- Loss of a hand or a foot
- Motor neurone disease
- A stroke
- Parkinson’s disease
- Heart attack
- Coma
- Certain types of cancer
- Motor neurone disease
- Heart valve replacement or repair
- Coronary artery by-pass grafts
- Benign spinal cord tumour
- Progressive supranuclear palsy
- Traumatic brain injury
How Do I Find the Best Rates and Deals?
It is essential to shop around when considering insurance coverage. Rather than going directly to an insurer, an independent broker such as Insurance Hero, which isn’t tied to any one insurer, will do the heavy lifting by searching the market and multiple insurers to get the best advice and quotes.
Insurance Hero has experience providing business protection insurance to businesses of different sizes. As an independent broker, we are not tied to any insurance provider.
We have relationships with all the top insurers, including Zurich, Aviva, Aegon, LV, and L&G, to ensure we can offer competitive quotes tailored to your business’s needs.
For a fast, free quote, contact our friendly, professional team of advisers at Insurance Hero on 0203 129 88 66 today. We want to help you protect your company and your staff by providing peace of mind in the event of your absence.
Other Types of Related Insurance
Business loan protection insurance is a critical cover to protect the interests of your business, but did you know that different types of related insurance cover can protect your company:
Keyman insurance
Keyman insurance provides cover if a key staff member dies or becomes critically ill and can no longer work.
Keyman insurance is available to businesses of all sizes, from sole traders to medium- and large-sized limited companies.
It helps maintain the business’s viability should something happen to the critical person, whether the founder or an essential sales manager.
A lump sum payout would be due in return for monthly premiums. This payout may be used to maintain the supply chain if costs increase, providing a financial buffer against a fall in profit or the cost of recruiting and training a replacement employee.
Shareholder protection insurance
Shareholder protection insurance provides other shareholders with a lump-sum cash payment to buy the shares of a deceased shareholder.
It is an essential form of insurance if existing shareholders need to maintain control so the organisation can trade profitably without outside interference.
Relevant Life insurance
Any payout from a Relevant life insurance policy differs, as it benefits the insured staff member, not the business itself.
If the insured dies, their dependents will receive financial compensation. Relevant life insurance is considered tax-efficient, as UK corporate relief applies to the premiums paid and the payout.
FAQS Section:
What happens if I die before the policy is set up?
Most insurers will automatically include an accidental death benefit should you die after an application submission, but before the policy is in place.
Insurers usually pay out for up to 90 days after receiving a business loan protection application.
A similar type of cover, immediate cover, provides protection before a policy is fully set up and typically lasts up to 60 days.
Can I change my policy once it is in place?
Insurers will typically include the ability to change your policy, known as a guaranteed insurability option, as part of the cover.
This means you can increase your insurance coverage if an existing business loan is extended, without needing further medical evidence.
What is Legal & General business loan protection?
Legal & General business loan protection offers both level and decreasing cover options, so the amount insured can match the business’s outstanding debt or decrease alongside loan repayments.
Businesses can also add critical illness cover for broader protection, and the plan provides an immediate accidental death benefit while the application is processed.
External sources related to this topic:
- https://www.legalandgeneral.com/insurance/business-protection/business-loan-protection
- https://www.zurichintermediary.co.uk/business-protection
Steve Case is a seasoned professional in the UK financial services industry, with over twenty years of experience. At Insurance Hero, Steve is known for simplifying complex insurance topics, making them accessible to a broad audience. His focus on clear, practical advice and customer service excellence has established him as a respected leader in the field.
