
Life Insurance For Scaffolders Quotes


Scaffolders often play a critical role in building large residential, commercial, and industrial projects.
Do you need life insurance as a scaffolder?
Scaffolders don’t legally need life insurance, but we recommend it because of the higher risks of working at height and with heavy equipment.
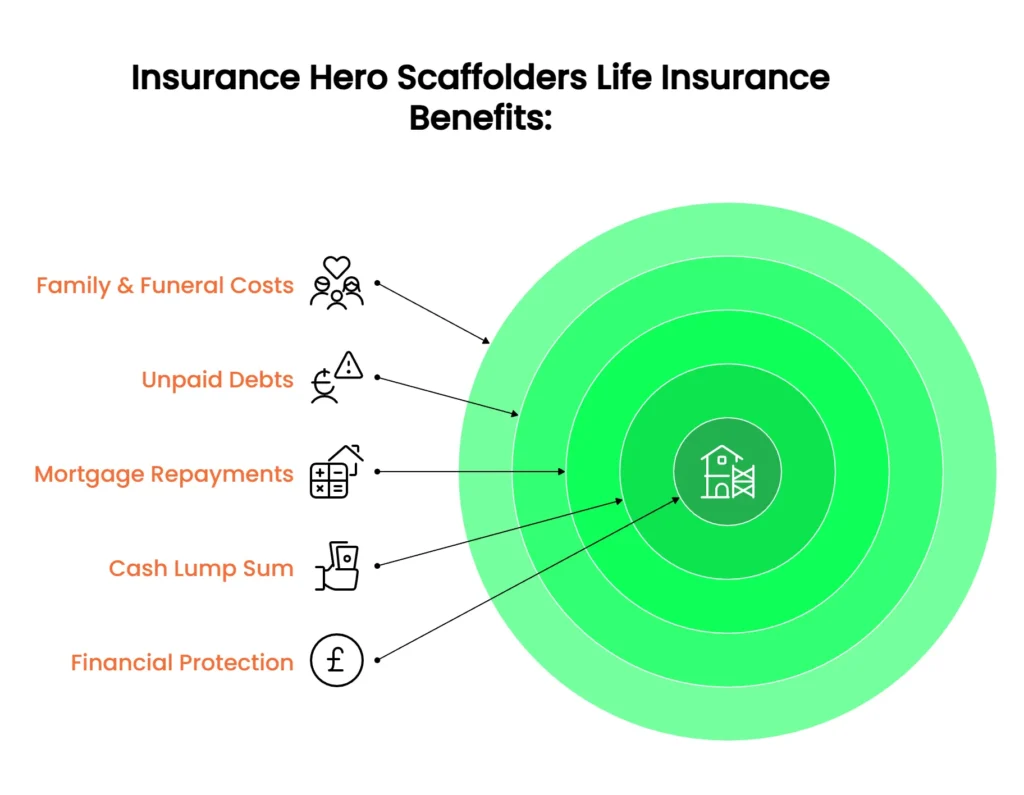
A policy can protect your family financially by paying a lump sum to cover mortgages, bills, or dependents if you die during the term.
If you’ve been declined before, a specialist like Insurance Hero can help you compare insurers and find affordable life insurance for scaffolders suited to your work.
Related Questions:
- Can scaffolders get life insurance? Yes, and usually with standard terms. However, higher-risk occupations may affect premiums.
- How does working at height impact my insurance? Working at heights over 40 feet may require specialised providers and higher premiums.
- What information do I need to provide? Job role, height worked, use of machinery, health status, smoking status, and medical history.
- Can I reduce my premiums? Yes, by maintaining a healthy lifestyle, opting for lower coverage, and comparing quotes from multiple providers.
- Do domestic and commercial scaffolders pay different life insurance rates? Commercial scaffolding is usually considered higher risk because of larger sites and greater working heights. This can increase premiums compared to domestic scaffolding work.
Compare Life Insurance · Help at Every Stage · Simple Quote Process
Some Great Reasons To Consider Getting A Free Quote Today:
- Affordable policies, meaning you will be able to find one that fits your budget
- Secure a policy tailored specifically for you as a scaffolder. Be fully protected, whatever happens
- Outstanding reviews for customer care
- Policies with excellent rates for shared cover
- There is no obligation to continue after getting a free quote
- Friendly and simple service
- Favourable treatment for smokers and vapers
How Do Life Insurance Providers View This Occupation?
A scaffolder’s main duty is to build a sturdy and safe framework for other workers to complete jobs at extreme heights.
Understanding how insurance companies and agents view scaffolding can often help individuals secure the coverage they need at an affordable price.
Insurance providers consider several factors when deciding whether to cover an applicant and what monthly premium they must pay for that coverage.
Here, we will discuss the factors to be considered and the options available to those in a scaffolding occupation.
Life Insurance Information for Scaffolders
Height is often the main factor that insurance providers consider when reviewing a scaffolder’s life insurance application.
Scaffolders who work at lower heights, generally 40 feet and below, can expect standard life insurance terms.
Scaffolders working above 40ft may pay slightly more for a policy.
Scaffolders working at higher heights may need to submit an application to an insurance provider specialising in high-risk occupation coverage.
Insurance providers also consider travel if the scaffolder works abroad, which can affect coverage decisions and the calculation of the monthly premium.
Several specialised insurance providers are willing to work with those in the scaffolding occupation.
Insurance Hero can match workers with providers willing to offer standard life insurance terms, even in high-risk occupations.
Do insurers consider the use of equipment and machinery?
Yes. Regular use of heavy machinery, powered tools, or hazardous materials can increase risk ratings when combined with working at height. However, these rarely contribute to excessively priced premiums.
Do insurers treat self-employed scaffolders differently?
Insurers usually assess self-employed scaffolders similarly to employed workers, but income stability and reliance on personal earnings may affect cover recommendations.
Types Of Cover Available
| Policy Type | Description | Key Features |
|---|---|---|
| Term Life Insurance | Coverage for a specified term. Fixed or decreasing sum assured. | Affordable premiums, customisable terms. |
| Whole of Life Insurance | Coverage for the entirety of the insured’s life. | Guaranteed payout, estate planning. |
| Over 50s Life Insurance | Guaranteed acceptance for those aged 50-85. | No medical exam, fixed premiums. |
The Typical Six-Step Process
| Step | Description |
|---|---|
| 1 | Insurance Hero will research and compare insurance providers on your behalf |
| 2 | Get quotes and evaluate policy options based on personal and occupational risks. |
| 3 | Fill out the application form and disclose all relevant details. |
| 4 | Undergo any required medical examinations. In many cases, this won’t be required |
| 5 | Review and finalise the policy terms and premiums with the provider. |
| 6 | Receive policy documents and ensure all details are accurate and up to date. |
Income Protection Information for Scaffolders
Income protection is also something scaffolders consider, given the higher risk they run of being injured.
Income protection is a policy that, if you become critically ill or injured to the point where you cannot work, pays out to provide financial support for living expenses.
How a scaffolder approaches the definition of this coverage is key. Scaffolders can secure income protection on standard terms when they define their occupation.
Another way to approach income protection is with an any-occupation or suited-occupation definition.
While these have advantages, insurance advisors often encourage scaffolders to use their own occupation definition whenever possible.
Applicants will also be given deferment period choices, usually between four and 52 weeks. During the deferment period, the individual stops working, and the claim is paid.
When choosing a deferment period, consider your employer’s additional benefits, current savings, and total living expenses.
Critical Illness Cover Information for Scaffolders
Companies offering critical illness cover will also want to know the height at which a scaffolder works when considering providing a policy.
Those working at lower heights, 40 feet and below, are generally offered critical illness cover at standard terms.
Those working at higher heights may need to apply with a specialised insurance provider.
Insurance Hero can help you find a critical illness cover provider that offers standard terms regardless of your working height.
Even if you are working in a self-employed capacity, we are confident we can secure the best policy for your needs.
Useful references:
- https://oculus-group.co.uk/scaffolding-safety-in-the-uk/
- https://www.gov.gg/scaffolding
- https://www.vitality.co.uk/life-insurance/guides/high-risk-occupations/
Steve Case is a seasoned professional in the UK financial services and insurance industry, with over twenty years of experience. At Insurance Hero, Steve is known for his ability to simplify complex insurance topics, making them accessible to a broad audience. His focus on clear, practical advice and customer service excellence has established him as a respected leader in the field.
