
Income Protection Insurance For Contractors


Do you worry about how you will pay the bills if you cannot work? Do your loved ones face financial hardship without your monthly income?
Our guide to contractors’ income protection insurance is essential reading. Learn how a modest monthly payment can replace your salary and give you complete peace of mind.
With many people becoming economically inactive due to long-term illness, income protection insurance provides a safety net to maintain your standard of living.
Contractors Income Protection Benefits
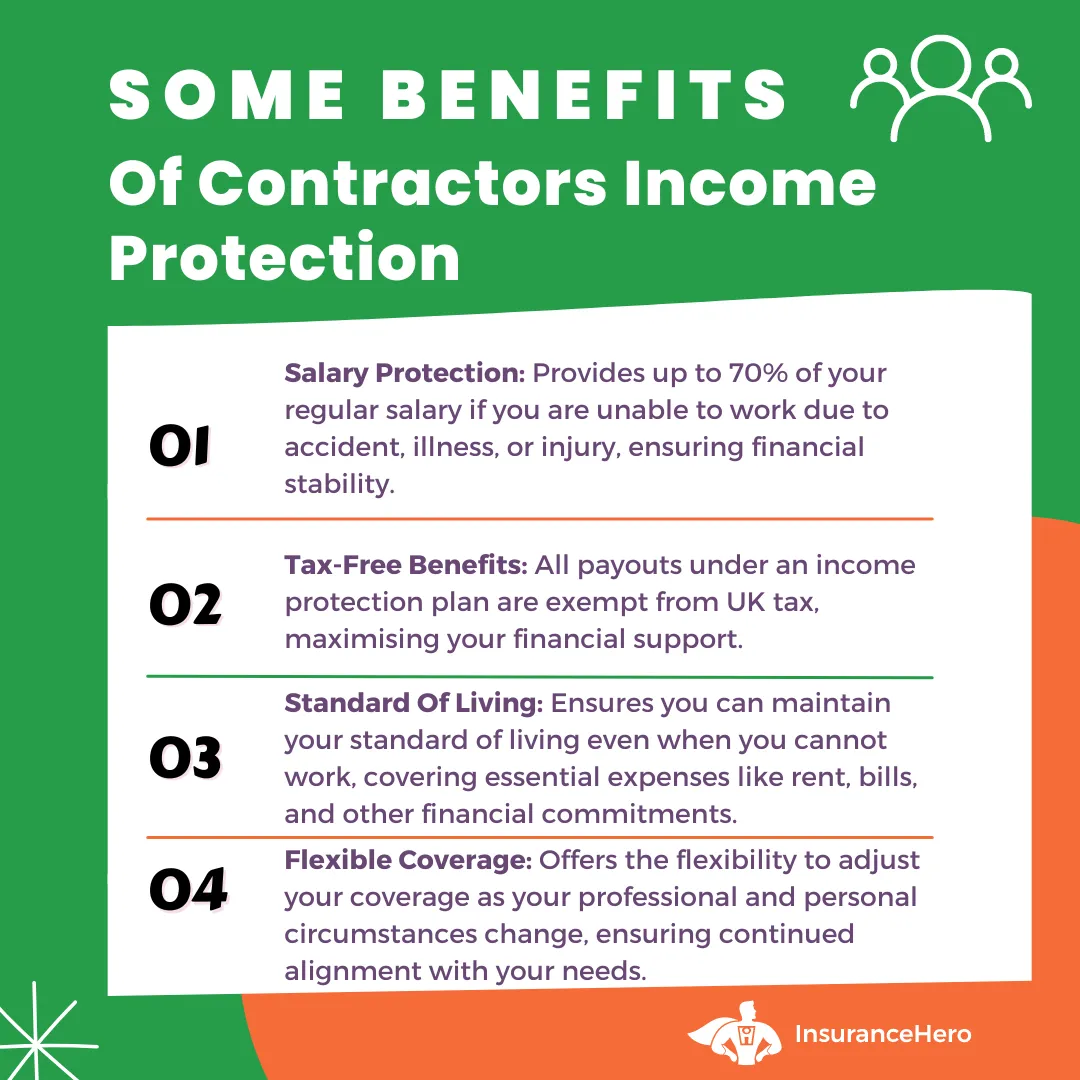
Protect Your Income. Get up to 70% of your income in monthly, tax-free payments to help maintain financial stability.
Insurance Hero can help you find the best, cost-effective policies that match your needs.
Here’s why you should consider it:
- Housing Expenses: For covering rental or mortgage payments
- Utility Bills: Such as electricity, water, gas and phone bills are covered
- Daily Living Expenses: Could include groceries and food delivery costs
- Flexible Coverage: To align with your lifestyle choices and requirements
- Vehicle & Travel: Pay towards road tax, MOTs, and fuel
- Waiting Periods: You can choose a time scale before payments commence, which can range from 4 weeks to 2 years, allowing you to tailor the policy to your needs
Income Protection Insurance From Trusted UK Companies. Quick Form. Start The Process Online
Why Do Contractors Need Income Protection?
As a contractor working as a sole trader or through a limited company, you are unlikely to have the sick pay policy businesses offer employees.
Depending on the industry, an employee may be paid anywhere from 1 month to 1 year of their salary while off sick.
As a contractor, if you cannot work due to illness or injury, you would receive the UK government sickness benefit, a payment of just under £100, payable for up to 28 weeks.
Depending on your ailment, you may be eligible for further disability allowances. However, for many, these low weekly payments are insufficient to maintain a reasonable standard of living.
Income protection insurance closes the earnings gap if you cannot do your job.
Is Contractor Income Protection Relevant To Your Situation?
As a contractor, make sure you are financially secure if you can’t work because of an accident, illness, or injury. To understand if income protection is for you, consider the following:
Savings
Do you have enough savings as a contractor to last a year without working? Injury or illness could keep you out of work for a long time.
Financial commitments
Do you have financial obligations that may come under pressure if you’re unable to work? These include mortgage payments, personal loans, school and university fees, and general month-to-month living expenses.
Supporting partner
If you’re out of the workplace, does your partner earn a good salary that could cover any shortfall in your earnings?
How Much Does Cover Cost Per Month?
The following table provides sample quotes for a self-employed plumbing contractor who doesn’t smoke and is in fair health.
They are earning an annual income of £45,000. The coverage extends until age 70, with a 4-month deferral period and a 12-month payment period.
| Age | Monthly Cost (£) |
|---|---|
| 20 | 7.82 |
| 25 | 9.46 |
| 30 | 10.21 |
| 35 | 11.63 |
| 40 | 13.14 |
| 45 | 15.49 |
| 50 | 17.84 |
While costs vary, many contractors can find well-priced coverage online. The protection is often worth it, given the lack of employer sick pay for contractors.
How can Insurance Hero Help?
Insurance Hero provides income protection coverage to contractors and the self-employed.
Here are a few of the reasons why we can help you:
- Insurance Hero is an independent insurance broker. We aren’t tied to any underwriter; our service is completely impartial. This lets us find you competitive income protection insurance for contractors, tailored to your circumstances.
- As brokers, we have greater negotiating power with insurers and can offer lower premiums than you can when going direct.
- Our caring team will fully support you through the claims process, should you make a claim, ensuring it runs smoothly and helping you receive a prompt payout.
Contact Insurance Hero today on 0203 129 88 66 for your contractor income protection quote. Our friendly team will work with you to provide a quote tailored to your circumstances; we want to ensure your plan is watertight. Your policy is our top priority!
Understanding the Main Policy Features
As a contractor, your broker should craft a policy relevant to your situation. Understanding what is relevant to you will help you make an informed decision before starting a plan.
Below are both standard terms and additional features that you should know. Your broker may be a generalist and may not understand the intricacies of working as a contractor or specific medical inclusions relevant to your circumstances.
Deferral Period
It is the time lapse between submitting a claim and activating your replacement salary. For employees, this ties in with an employer’s sickness policy.
A contractor is self-employed and will need to gauge the deferred period with their finances and how long they can afford not to work.
The longer the deferred period, the lower the premium. Conversely, the shorter the deferral period, the higher the monthly premium cover.
Level of Cover
Self-employed contractors are typically sole traders or operate through a limited company of which they are a director.
Sole traders should choose a personal policy that allows coverage of up to 60% to 70% of their regular salary should they be unable to work.
Company Directors can opt for a plan that provides up to 80% salary coverage. A separate section covers director income protection insurance later in the guide.
Cease Age
How old will you be when your contractor income protection policy matures? It is normal to align the plan end date with your retirement date.
The later you leave it until retirement, the more expensive the cover becomes. Insurance providers offer coverage up to age 70. Premiums will be higher than coverage for individuals retiring at 60 or 65.
Length of Claims Period
It is the period that a replacement salary will cover throughout a policy. Short-term cover typically pays out for 1 to 5 years.
The longer the payout period, the higher the coverage cost. Long-term cover differs in that it provides the sum assured until retirement, should you no longer be able to return to the workplace.
Studies show the average claim period in the UK is just under 8 years.
This suggests that taking out a long-term contractor income protection policy is a sound recommendation. Insurance Hero adheres to this view.
Premium – The Cost of Cover
It is the cost of cover in contractor income protection insurance. It represents a monthly amount paid throughout a fixed-term plan.
Guaranteed Premiums
The monthly premium is ‘guaranteed’ to remain the same for the policy term. The insurer cannot change the premium level unless the policyholder requests it.
This premium type can help if a policy begins when the policyholder is young and has no notable medical conditions.
Reviewable premiums
An insurer can review the premium level at any time, typically due to unexpected circumstances. Reviewable premiums start cheaper.
Upward revisions, however, usually make the policy premiums increasingly expensive over the policy duration.
Age-banded premiums
This type of cover amount rises as the policyholder gets older. It links higher age to a greater likelihood of a claim.
Age-banded premiums start low and increase progressively over the policy term.
Indexation
Indexation is an integral part of life insurance, including income protection cover. The insurer uses inflation as a benchmark to raise insurance premiums.
The Consumer Price Index (CPI) or the Retail Price Index (RPI) are popular references in the UK.
There are three types of premium cover available:
Level
For the duration of the income protection for contractors policy, the premium and the subsequent replacement salary remain the same.
Increasing
Both premium and salary coverage increase incrementally throughout the policy, in line with inflation.
Decreasing
The premium decreases throughout the insurance period. It can be helpful if it protects financial commitments, such as a mortgage, which also has a fixed maturity date and reduces over time.
Additional Cover Features
You should be aware of other standard features and optional features of income insurance cover before taking out a UK policy.
Death benefit
If you die while receiving income benefits, this feature allows designated beneficiaries to receive a lump-sum payout.
Specified injury or trauma
A specific type of illness or injury can be included at the start of a personal plan. You may receive an additional payout if you can’t work because of this condition.
The extra payment is usually added to the regular amount when a claim occurs, but sometimes it is paid as a lump sum.
Childcare benefit
If you cannot work, the childcare benefit pays out a further fixed amount for each child specified in the policy. This additional payout helps cover other nursery, childminder, or nanny costs.
Freezing Insurance
As a contractor, you may have periods between jobs or choose not to work. Pausing can be useful until you are back working.
The policy doesn’t pay if you are not working, and paying monthly premiums makes no sense; that’s why freezing is beneficial.
Involuntary Dismissal
It is perhaps just as relevant for a self-employed contractor as an employee of a company, and worth being aware of.
Some insurers will include involuntary dismissal as an additional option to a policy. If you think your job warrants this, it is worth speaking to your insurance broker to learn more.
What Comes Under Self-Employed Income Protection?
If you are a self-employed contractor, contractor income protection can provide a replacement salary when you cannot work.
Income protection covers against a wide range of illnesses, injuries and accidents, but there are areas that you should be aware of that are not covered:
- When an incident occurs, if you are working overseas in a country or location not included under the initial terms, this may stop any payout
- Any participation in high-risk activities or extreme sports not declared at the beginning
- Alcohol or drug abuse
- If you are pregnant and in childbirth
Pre-Existing Medical Conditions
Declaring pre-existing medical conditions is important when you start a plan.
An insurer will have to be aware of any medical issues within the last five years, and these are interpreted in any of three ways:
- The medical problem is excluded from the policy
- The medical condition provides coverage on standard terms
- The disease is covered, but results in higher premiums
Own occupation / any occupation
It is essential to understand how your insurer defines your job.
If you cannot work, different insurers define your inability to do your job differently.
There are three types of interpretation:
- Failure to do your job or a similar one that you are qualified for
- The inability to undertake your actual job
- Failure to do any paid work
Should you specify this in your policy, the highest level of coverage (and most expensive) is the inability to do your job.
Proportionate payment
A further feature you should be aware of is proportionate payment. If you return to paid employment but are in a lower-paid role, the policy can top up your earnings.
Company Director’s income protection insurance
Contractors who are sole traders can use a standard personal income protection plan.
A director’s income protection insurance policy is relevant for a contractor using a limited company.
All salaries and dividends are paid to a contractor through their limited company. The policy is set up in the company’s name, and the business pays the monthly premiums.
If a claim occurs, any benefit is taxed as income. This differs from personal plans, where the benefit is tax-free because premiums are paid from post-tax income.
Pre-tax income with a limited company can be up to 80% of a regular salary, compared to lower levels with a personal plan.
Insurance Hero is an independent broker that helps contractors with insurance policies tailored to their personal and professional circumstances. Contact our expert team of brokers today on 0203 129 88 66 for a competitive no-obligation quote. We are here to help you!
Understanding the Claims Process
If you cannot work and need to submit a claim as part of your income plan, here are the simple steps involved in the claim process:
Step 1: Contact your broker
Contact your broker or insurer and request a claim application form. You can contact us by phone, email, web chat, or written correspondence.
Step 2: Complete an application form
Once you receive the claim form, complete it and provide any requested information.
An insurer requires standard information, such as a GP report outlining the medical condition keeping you from working.
Additional financial information, such as payslips, P60S, business accounts and tax returns, is required. The information needed will depend on whether you are a sole trader or a limited company.
Step 3: How is a claim assessed?
The insurer will first check that your circumstances meet the policy’s criteria. The insurer will then check that the replacement salary is still correctly tied to your salary when you stopped working and verify other payout requirements.
Step 4: Once a claim receives approval
Once an application is signed off, you will receive a call to confirm your bank payment details and the date the first payment will occur.
Until this happens, you must keep paying your monthly premiums per the policy. We will review the claim periodically until you are able to return to work.
FAQs
Why is my replacement salary not adequately covered?
This insurance type caps the amount of your regular income you can receive under the plan.
The reason is simple. It will encourage a claimant to return to work. The policy is not to put you in a better financial position than working.
Income insurance for contractors rarely goes above 70% for personal plans, and you can choose a lower level of coverage to keep premiums down.
Is unemployment insurance for all contract workers?
The answer is yes. You can take out a policy regardless of whether you are a contractor operating as a sole trader or using a limited company.
The requirements are: being 16 or older, registered to pay UK tax, registered with a UK medical practice for the last 3 years, and having a UK bank account.
Is Income Protection the same as ASU?
No, they are not the same. Accident, sickness and unemployment cover is a cheaper alternative. It doesn’t offer a long-term option and doesn’t include full medical underwriting.
For contractors, are there other alternatives to full income protection cover?
Yes, there are alternatives, typically lower cost but less comprehensive:
- Accident and sickness insurance: Low-cost cover which covers accidents as well as illness
- Sickness insurance for contractors: A cheaper alternative for contractors; this is just coverage for illness
- Unemployment insurance for contract workers: Specifically covers events in the workplace
- Redundancy protection cover: Its sole purpose is to protect against involuntary dismissal.
- Mortgage payment protection: Consider this if your main concern is protecting your mortgage payments against a possible job loss.
What is the cost of income protection contractor insurance?
Without a quote, it’s hard to answer, as many variables affect the cost.
These include some of the following:
Factors include the claim period, your age and any underlying medical conditions, the percentage of salary covered, the duration of the policy and whether you want the plan indexed to take inflation into account.
How flexible is income protection to changing circumstances?
Insurers understand that your circumstances will evolve over your working lifetime as a contractor. If your circumstances change, you can change your policy.
Changes in your private and professional life may include a new mortgage, the birth of a child, or an increase or decrease in salary.
Contact your broker whenever you think a change in circumstances may affect your contractor’s income protection policy.
Can I have more than one protection policy?
Yes, this is possible. There are genuine reasons someone may choose to have more than one policy.
What should be noted is that any payment benefit resulting from all your total benefit claims cannot exceed 75% of your regular salary.
Can you get a policy if you have an existing injury?
Yes, this should be fine. You must declare your pre-condition at the outset of your policy—the extent or type of injury impacts how an insurer will consider it.
There are three ways an insurer deals with a pre-existing injury. Firstly, they may exclude it altogether from coverage.
They may also include it at an additional premium, or accept the condition at standard rates.
Are income protection and critical illness different?
Yes, they differ fundamentally. Income protection insurance for contractors pays out a monthly benefit of up to 70% of your regular salary.
It aims to help you return to work. Critical illness provides a one-off lump sum payment if you live longer than ten days after diagnosis. It assumes you may never return to work.
Other income protection pages (by occupation):
Income Protection Insurance For Dentists
Are you a self-employed or an NHS dentist? Do you worry about what would happen financially to you and your loved ones i…
Income Protection Insurance For Doctors
Income protection insurance for doctors provides a replacement salary if you cannot do your work because of an illness o…
Joint Income Protection Insurance for Dual-Income Couples
If you’re in a similar situation to 25% of couples with a dual income, you’ll never have even contemplated Income Pr…
Can You Get Group Income Protection Insurance?
Are you worried about how you’ll cope financially if illness or injury stops you from working? In 2024 alone, in…
Self-Employed Income Protection Insurance
Working as self-employed can be immensely rewarding if a business becomes successful and, with no employer or boss to re…
Income Protection Insurance For Vets
Being a vet can be challenging yet immensely satisfying. Workplace accidents and injuries can happen; however, if you…
Income Protection Insurance For Contractors
Do you worry about how you will pay the bills if you cannot work? Do your loved ones face financial hardship without you…
How Much Does Income Protection Insurance Cost?
While most people aim for the most cover at the lowest cost, the actual cost of income protection insurance isn’t that…
Income Protection Insurance For Teachers Guide
Receive a monthly income for as long as you need if you are off work sick or physically injured – it is that simple. …
Does UK Income Protection Insurance Cover Maternity Costs?
If you’ve just learned that your family is about to grow, there’s a good chance you’re filled with both tremendous…
Does Income Protection Cover Redundancy?
When times are tough, the economy turns downward, or corporate profits demand reduced expenses, employees often suffer. …
What Is Accident, Sickness, and Unemployment Insurance (ASU)?
When it comes to safeguarding your family and your future, two major transition points matter. The first is any …
Steve Case is a seasoned professional in the UK financial services industry, with over twenty years of experience. At Insurance Hero, Steve is known for simplifying complex insurance topics, making them accessible to a broad audience. His focus on clear, practical advice and customer service excellence has established him as a respected leader in the field.
