
Life Insurance For Mums 2026 Prices
Losing a parent would turn any child’s world upside down.
Without Life Insurance, your family could face distressing changes. If paying the mortgage or rent becomes too much, they may have to move house. If the family had to relocate, the children might also have to change schools.
But if you don’t have sufficient life insurance for mums, the distress could be far worse. At a time of loss, the last thing a family needs is financial worries.
With coverage that suits your circumstances, your loved ones wouldn’t need to worry about paying the bills. They could also afford everyday expenses that maintain the quality of life they’re used to.
Here’s why insurance is worth considering:
- Generally, Life Cover is used to help families adjust to the financial changes that occur when a parent dies, helping the family survive the financial shock that death brings.
- The biggest single financial change is usually a significant drop in income. The amount by which a family’s income drops (and the resulting financial consequences) varies from family to family.
- A family can also use Life Cover to repay debt. These may include mortgages, bank loans, credit cards and car loans. By using Life Insurance to clear these debts, the family will need less income to cover ongoing financial and lifestyle commitments.
Mums, Help Protect Your Family’s Future · Compare Top Insurers
Which policy type fits your current situation?
Types of Life Cover with a Fixed End Date
Also known as ‘term assurance’, many life insurance policies have a fixed end date, which you choose when you take out the plan:
- Level cover pays a lump sum, and the cover amount stays the same throughout the policy.
- Decreasing cover pays a lump sum, and the cover amount decreases over the policy term. This type of policy is used for repayment mortgages.
Life Cover With No Fixed End Date
A Whole-of-Life plan has no fixed end date, offers a guaranteed payout, but is usually more expensive.
Cover if you survive but are seriously ill
In this scenario, Critical Illness Cover (add-on or standalone) might be your best option.
Critical illness cover is an insurance policy that pays a tax-free lump sum if you’re diagnosed with a specified serious condition (like cancer, stroke, or heart attack) during the policy term.
You can combine either policy type. For advice on your specific situation, speak to an FCA-regulated adviser or request a call-back from one of our team members.
Alternatively, you could use MoneyHelper’s free service if you are looking for further information and are not yet ready to take out coverage.
Current Costs Of Cover Per Month
Below is an illustrative price comparison of a Mums term policy with a decreasing term insurance policy.
These are quotes for a £100,000 policy, cover 30 years, and are based on a healthy non-smoker.
Level Vs Decreasing Term Cover
| Your Age* | Level Term Life Insurance | Decreasing Term Life Insurance |
|---|---|---|
| 20 | £4.56 | £4.71 |
| 25 | £5.26 | £4.98 |
| 30 | £5.83 | £5.09 |
| 35 | £7.91 | £6.04 |
| 40 | £10.39 | £7.56 |
| 45 | £16.32 | £11.82 |
| 50 | £27.81 | £18.10 |
Below is an example of a price comparison between single insurance policies and a joint policy. These quotations are based on a policy that provides £100,000 in cash sum coverage over 30 years for non-smokers in good health (no pre-existing conditions). For more information relating to coverage for smokers, please click here.
For a modest extra cost, a working mum can get income protection insurance from the same insurer, protecting household income.
Life insurance experts like Insurance Hero can help you replace lost income to cover mortgage payments, up to your existing annual income.
Single Vs Joint Policies
| Your Age | Two Single Life Policies | A Joint Life Policy |
|---|---|---|
| 20 | £9.11 | £7.35 |
| 25 | £10.54 | £8.20 |
| 30 | £11.63 | £10.24 |
| 35 | £14.81 | £15.08 |
| 40 | £18.83 | £21.40 |
| 45 | £26.74 | £30.28 |
| 50 | £54.62 | £56.55 |
Below is an example of an insurance policy price comparison between a smoker and a non-smoker in good health. The quotes are based upon a £100,000.00 level term policy over 30 years.
Smoker Vs Non-Smoker
| Your Age | Smoker Per Month Cost | Non-Smoker Per Month Cost |
|---|---|---|
| 20 | £5.87 | £4.56 |
| 25 | £7.24 | £5.36 |
| 30 | £9.73 | £5.91 |
| 35 | £13.52 | £7.96 |
| 40 | £18.64 | £11.38 |
| 45 | £24.74 | £16.35 |
| 50 | £47.12 | £28.83 |
Premiums verified: 11th May 2026. Source: Aviva
Life Insurance For Single Mothers
Are you a new mum, a single mum, a stay-at-home mum, or the sole family breadwinner? If so, you should consider life insurance for a single mum.
Optional children’s cover as well as critical illness cover. Chosen by 1000s of happy parents in the UK. Insurance Hero proudly offers some of the best life insurance for single mums without gimmicks and hidden extras.
The Cost of Childcare Support
Whether you are a stay-at-home mum or work outside the home, you know how time-consuming childcare is.
A family with the terrible misfortune of losing its mum would have to pay at least £28,000 per year in childcare support to make up for the care she would have provided.
Losing a parent is a life-changing event for a child, let alone losing two.
It is hard to think about such things, but according to 2021 Child Bereavement Network data, in the UK, about 26,900 parents pass away each year while raising dependent children. That’s roughly one parent every 20 minutes.
The pain of losing a parent cannot be erased quickly; only time can heal it. Fortunately, the financial implications of such a terrible loss need not be added to the already harrowing grief.
It is better to be prepared for such eventualities. Having your finances in place will provide your partner with much-needed relief.
Why Consider Life Insurance?
Simply, to take care of your family. To make sure they are taken care of if something happens to you.
If you purchase a whole of life insurance or term insurance and the payments are made each month, you will make sure that your family is provided for when you are no longer around.
Whole of life insurance for mums lasts your whole life, while a term insurance policy lasts for a set period, around 25 years.
Your family can put money towards the children’s future, while also reducing the cost of paying professionals to do the work and the tasks you used to do as a mum.
Dealing with Life Insurance Changes after Divorce
Most breakups aren’t easy. They’re even more complicated when the relationship lasted years and involved a home mortgage, joint finances, joint life insurance policies, children, and Wills.
It’s a lot for any parent to deal with, but it must be done.
When the dust settles and you’re ready to separate your finances, you need to know what you can and can’t do.
What you cannot do on a joint life insurance policy after you’ve separated is keep it. The only exception is if you have a “separation benefit”.
Without that, the policy needs to be either cancelled or amended. The best way to determine how to proceed is to compare the cost of starting a new policy with the cost of keeping the existing one in place with amendments.
Changing your single mum life insurance policy may change the pricing
The premiums will likely reflect that because you’re changing from a joint policy to a single policy.
It may drop in price because, theoretically, the insurer’s risk is halved when someone is removed from the policy. But then again, the insured’s income level will also differ.
Can you take out a single additional policy on your ex-husband or ex-wife?
To take out an affordable life insurance or critical illness cover policy on someone else, it is required that they have a financial association with you.
In a divorce, that may not be the case, but it will be if child maintenance payments are involved.
You can’t take out an insurance policy without your ex-spouse knowing about it. Secret policies don’t exist, and they can’t, because insurers require consent to access medical records.
Other situations in which taking out a policy following a divorce or the dissolution of a civil partnership applies are when spousal maintenance payments (known in Scotland as a Periodical Allowance) are in place.
If an ex-spouse makes regular payments to you towards living expenses or a repayment mortgage, there would be a financial interest in ensuring those payments with some type of life insurance policy.
The types of life insurance available when there is a financial interest
The two types that may have appeal are:
- Cash lump sum term
If you receive child maintenance payments, it makes sense to insure their value until they stop when the child turns 16 or 18.
For spousal maintenance or periodical allowance payments, the insurance term may be more appropriate, such as three years.
- Family Income Benefit
Instead of a lump sum paid by an insurer, as with a term life policy, a family income benefit policy would continue to pay a fixed monthly amount until the child reaches 16 or 18 years of age.
Changing the beneficiary on your policy
Irrespective of what your Will says, the beneficiary named on your life insurance policy is the person whose monies are paid, so if that’s your ex and you no longer want that to be the case, you’ll need to contact your insurance provider to have the named beneficiary changed.
Do you need to change your Will as well?
If you have a Will registered in England, you have a couple of options. You can either change your entire Will or add what’s called a Codicil.
This can be used to make minor changes to your existing Will, such as amending policy beneficiaries, although it can also be used to change the executor of your Will. Significant changes are often best done by writing a new Will.
Mum’s Life Insurance Financial Support Key Points:
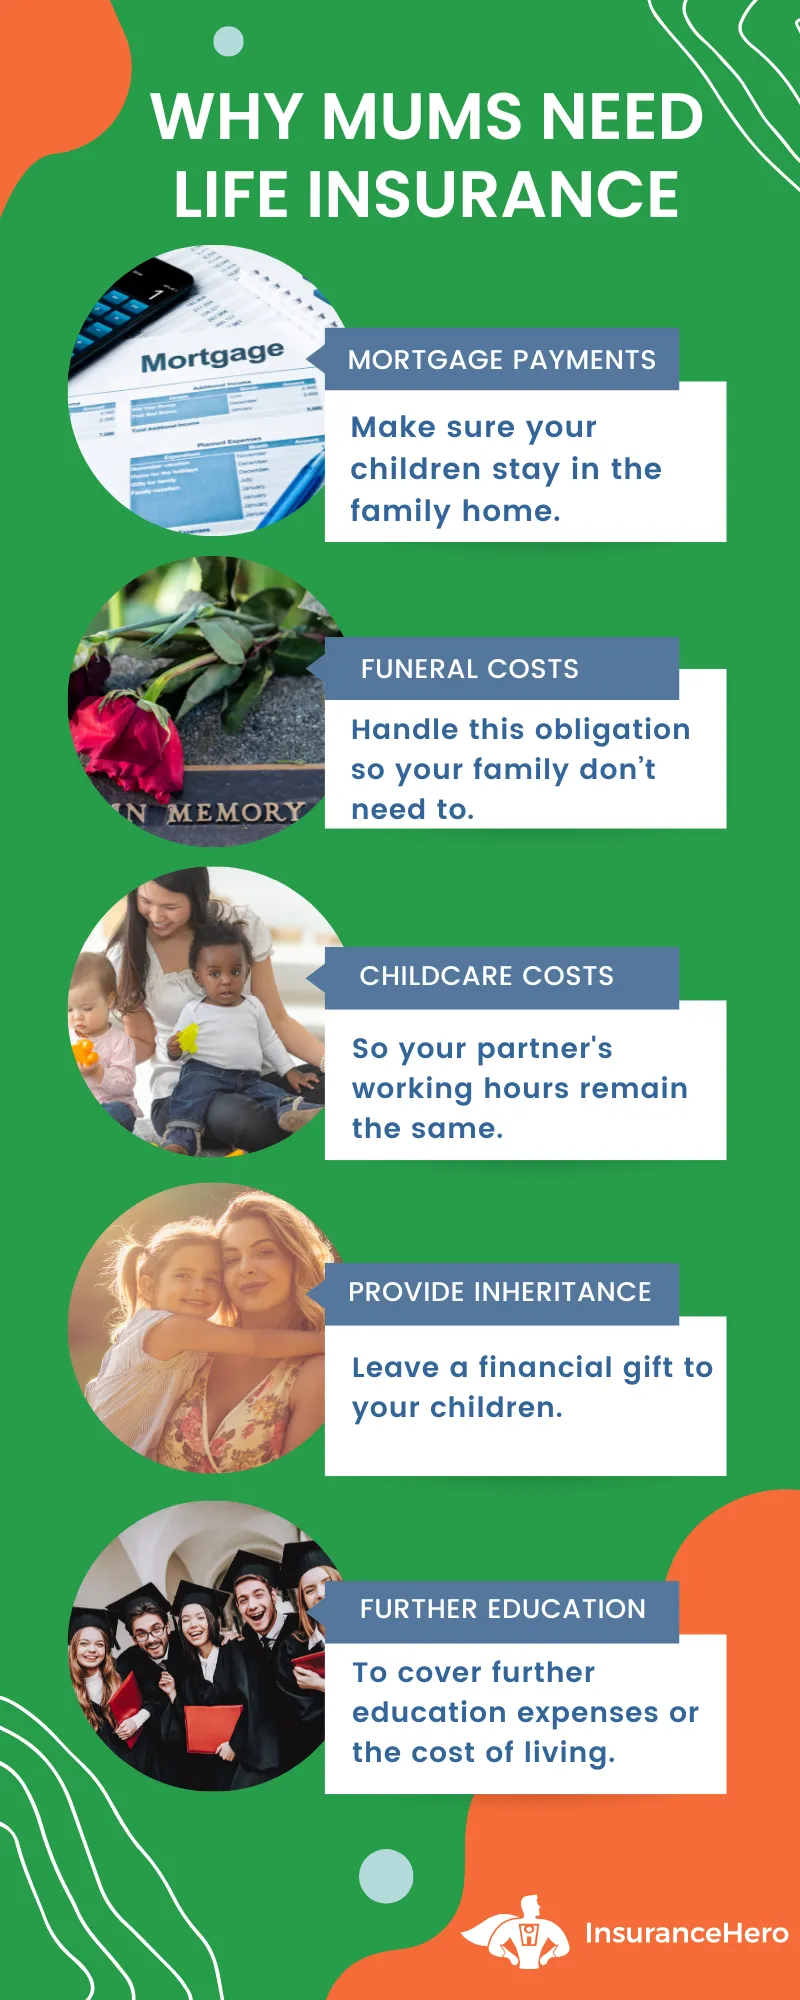
- Life insurance can provide financial security for your family if you die. Your loved ones can access policy funds to cover funeral expenses, debts, and other financial obligations.
- Many employers offer group life insurance plans, which can be an affordable option for mums who want to buy a policy but don’t have the time or resources to shop around for individual plans.
- Same sex couples are fine, and separate policies are not necessary. The surviving partner can pay the outstanding mortgage balance.
- You may need some help calculating the life insurance cover amount. But you must only buy life insurance you need.
- Some UK insurers offer free parent life cover plans, typically giving parents of young children £15,000 of coverage for 12 months at no cost. This is subject to eligibility. Aviva’s Free Parent Life Cover is one example. This is not a substitute for a full policy. Verified by Insurance Hero: 26/04/2026.
Related Reading: Depending on Your Personal Circumstances:
Benefits of Writing Your Life Insurance into a Trust
Understanding Family Income Benefits
What Cover Is Right For You And Your Financial Concerns?
It is beautiful to leave a legacy behind. Every mother wishes to care for her family forever, but this is not always possible.
A women’s life insurance, 50s life insurance, decreasing term insurance, level term life insurance or mum’s critical illness cover policy allows you to leave your family with one less burden, less stress, and the capacity to live happily, even if you are gone or suffer a terminal illness.
Try our mum’s life insurance calculator to compare quotes.
With free, no-obligation life insurance quotes from Insurance Hero, you can start your search, review your options, and see how much life insurance you might need.
Our free service can help explain which level of coverage best fits your circumstances.
The Benefits Of Young Mum Life Insurance Coverage
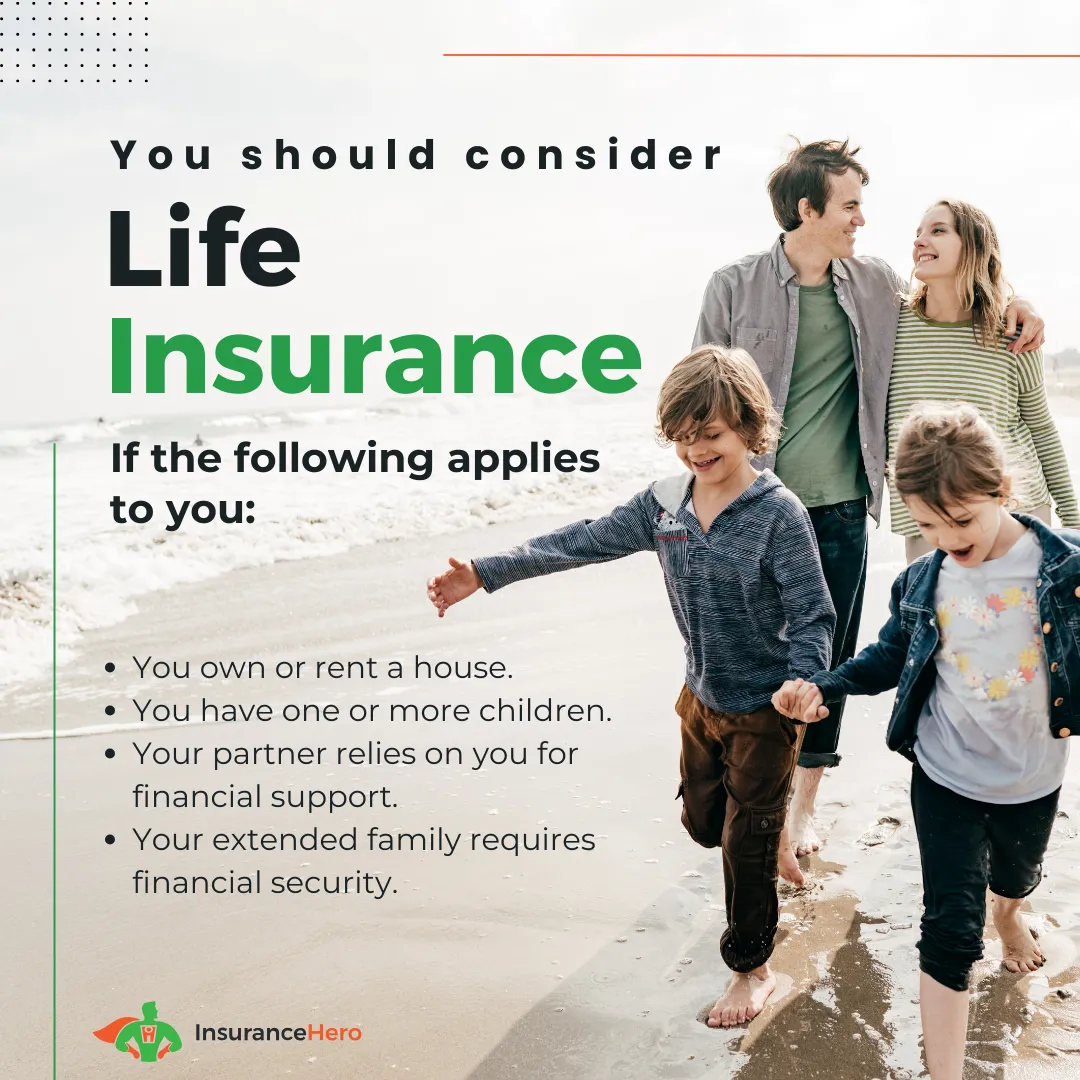
Financial Security for Children
Ensures that, if the mother passes away unexpectedly, her children will have financial support for their upbringing and education.
Debt Protection
Helps cover outstanding debts or mortgages, preventing financial burdens from passing to the family.
Income Replacement
Provides a financial safety net to maintain the family’s standard of living, especially if the young mum is the primary or sole breadwinner.
Affordability
Life insurance premiums are generally lower for younger people, making it a cost-effective way for young mums to protect their family’s future.
Can you get life insurance for mums with a free gift?
Insurance providers often offer promotional incentives, such as free gifts, to attract new customers.
These policies might include vouchers, cashback, or other bonuses. Mums looking for life insurance should research and compare policies and providers, paying close attention to the terms and conditions of any free-gift offers to ensure they align with their insurance needs and expectations.
We have a detailed guide on life insurance with free gifts that you might find interesting.
Life Insurance For Pregnant Mums
Obtaining life insurance during pregnancy is entirely possible. Expecting a child does not affect your ability to secure an insurance policy or the cost of your monthly payments.
You can start a policy at any stage of pregnancy. This helps secure your expanding family’s finances and provides peace of mind about their economic well-being.
Case Studies
Case Study 1: Sarah M, the Working Single Mother
Sarah is a 35-year-old single mother living in Manchester, UK. She works full-time as a nurse and is the sole provider for her two children, aged 7 and 10.
She had been considering life insurance for a while, but her job and busy family life kept pushing it back. After a health scare, she decided it was time to act.
In 2025, Sarah took out a term life insurance policy with us to provide coverage until her youngest child turned 25. The policy was affordable and fit into her tight budget.
She chose a life insurance policy for working mums that would pay out a lump sum large enough to cover her mortgage, her children’s future education costs, and provide them with a financial cushion.
The benefits for Sarah and her family were immediate. She felt relieved knowing that if anything happened to her, her children would be financially secure.
She knew the policy payout would cover the mortgage, ensuring her children always had a home. It also meant her children’s education would be covered, letting them pursue their dreams without the burden of student loans.
[Verified with customer consent, February 2026]
Learn more about critical cover for mums.
FAQs
Do mums need life insurance?
Mums can benefit from life insurance because they are more likely to have a family to care for and to be stay-at-home parents.
Is mums’ life insurance expensive?
No, insurance is not necessarily expensive. An individual’s life insurance premium depends on age, health, risk, and family history.
Compare costs between insurers to find the best value. It could be cheaper than a joint life insurance policy. The best time to buy life insurance is as early in life as possible.
How do I work out the cover amount?
Consider your children’s ages, the size of your mortgage or rent bill, household expenses, and other child-related costs, including private school fees and leisure activities.
Am I fearful of medical underwriting and the associated costs?
If you have a problematic medical history or pre-existing medical conditions, you can expect your monthly instalments to be higher.
However, it’s smoking that puts up people’s rates, not a previous medical issue that has been resolved.
Research references for separate policies and joint cover options:
- https://www.covermagazine.co.uk/news/3027805/-uk-women-dependent-child-life-cover
- https://metro.co.uk/2022/07/12/four-mums-reveals-the-true-cost-of-raising-a-child-16819208/
- https://www.aviva.com/newsroom/news-releases/2020/01/uk-first-time-parents-fail-to-financially-protect-their-families/
Steve Case is a seasoned professional in the UK financial services and insurance industry, with over twenty years of experience. At Insurance Hero, Steve is known for his ability to simplify complex insurance topics, making them accessible to a broad audience. His focus on clear, practical advice and customer service excellence has established him as a respected leader in the field.
