
What Is a SERP Pension And Should You Opt Out Of One?
Throughout the last decades, there have been many different options for pension schemes, both private and government-run.
Numerous pension changes have also been implemented, altering how they work.
Unfortunately, that means by the time you retire, the current landscape of pension schemes can be very different from the one you paid into and earned, and you need to be able to navigate both.
One pension you may or may not have accrued is the SERPS pension scheme. What is it, what do you need to know, and should you opt out if you haven’t already? Read on to learn more.
What is a SERPS Pension?
A SERPS Pension is the “additional state pension” but is more accurately known as the State Earnings Related Pension Scheme.
This was a secondary pension you could pay into throughout your working life, which would accrue credit and contributions for an additional state pension that would pay out on top of the standard state pension.
You could only pay into it if you were traditionally employed (self-employed individuals could not contribute), and you could not contribute below an earnings threshold.
The SERPS Pension was essentially automatic; anyone who earned full Class 1 National Insurance contributions earned credit towards the SERPS pension. However, not everyone contributed to the SERPS pension; more on that momentarily.
What Happened to the SERPS Pension?
If you’ve noticed the past tense in the section above, keep an eye out.
We use the past tense because the SERPS pension scheme ended in 2002. It ran from 1978 to 2002, but in its final year, it was changed to expand eligibility and ensure fairness.
Specifically, the SERPS Pension was replaced with the Second State Pension (S2P). The S2P expanded eligibility for those who could pay into the secondary pension, though it still didn’t cover self-employed individuals.
As if that wasn’t complex enough, the S2P program was cancelled in 2016 and replaced with the current state pension system, the New State Pension.
Could You Opt Out of the SERPS Pension?
Not everyone was happy to contribute to the state pension. For one reason or another, many people chose to pay into private pensions instead.
Rather than contribute even more on top of the basic state pension and SERPS pension, you could opt out – or technically, “contract out” – your SERPS pension contributions.
Essentially, you would still pay those contributions, but instead of going to SERPS, they would go to your private pension.
These protected-rights pensions were ideally larger than what you would get from SERPS, and because the government did not manage them, they also had potential secondary benefits.
For example, they could also lower the amount you and your employer contributed to NIC, putting more money in your pocket at the time.
Whether or not you opted out of the SERPS pension varied. Some workplaces and employers would automatically enrol you in their pension rather than SERPS. Some gave you the option to.
Some allowed it but didn’t advertise it, leaving it up to you to research, choose a private pension, and invest.
Note that you couldn’t opt out of the SERPS pension and keep the money; you had to invest it somewhere.
Overall, it can be hard to tell whether you contracted out of your SERPS pension without keeping track of that information, because the payments generally worked in the same automatic way and were largely seamless for workers.
If you contracted out of your pension contributions, the way they were governed, regulated, and handled over the intervening decade will have varied.
- If your payments were redirected to a defined contribution scheme, such as a personal pension, they were labelled protected rights and often subject to restrictions on how they could be used in retirement. These rolled over into standard pension benefits in 2012, when this type of scheme ceased to allow you to contract out your pension payments.
- If your payments were redirected to a defined benefit or final salary scheme, they usually had guarantees attached to deliver at least a specific minimum level of benefit, similar to what the SERPS pension would have paid. This helped protect you from ending up with less than you would have if you had not contracted out. These may also be guaranteed minimum pensions or reference scheme test benefits. The option to contract into these schemes was ended with the new state pension in 2016.
Can you still opt out of your SERPS pension? No, you can’t contract out, and the type of pension was ended. There’s no way to contract out or opt out of your SERPS pension scheme retroactively.
How Do SERPS Contributions Affect Your State Pension?
If you contributed to SERPS during your working life and are now planning your retirement and pension payments, you may face a complex situation you aren’t fully aware of.
This is even harder because many employers contracted out SERPS contributions without telling you, or only mentioned them in occasional statements you likely forgot or ignored.
If you reached retirement age before 6 April 2016, when the new state pension was introduced, you will receive the old essential state pension payments.
You may also be eligible for additional state pension payments, but the amount you receive will depend on whether you were contracted out of the SERPS pension.
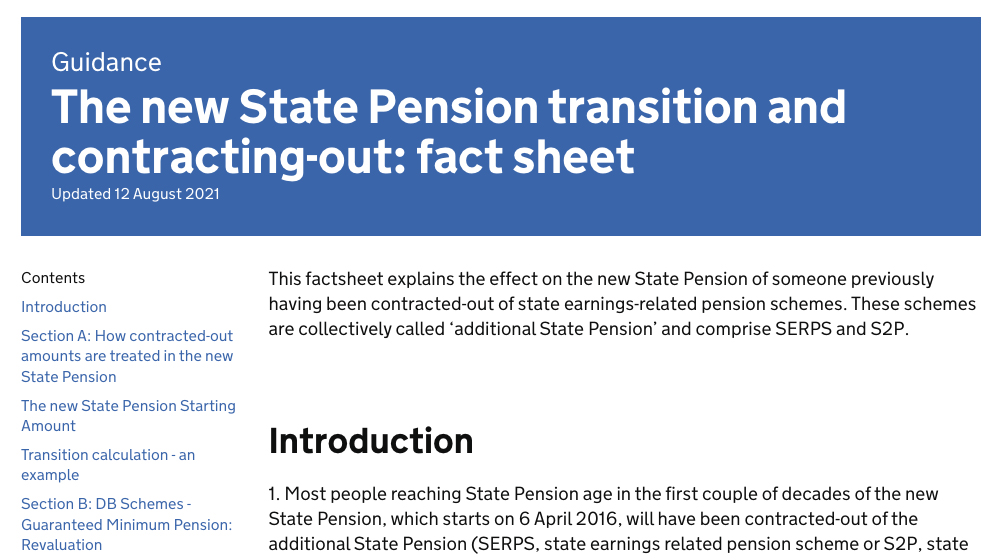
On the other hand, if you reached retirement age after 6 April 2016, or haven’t yet reached retirement age, you will receive the new state pension instead. This pension may also be reduced if you were contracted out of the SERPS pension scheme.
This is meant to be a simpler system, though if you’re right on the cusp of the transition, it often doesn’t feel that way.
To put it all in simpler terms:
- Everyone receives some amount of state pension.
- Everyone who pays into SERPS will receive some additional pension on top of the standard state pension.
- Everyone contracted out of the SERPS pension scheme will receive less of those additional payments, or none at all, but will likely receive a private pension instead. This may or may not be more than what you would otherwise have received, and it may or may not have additional rules on how it can be disbursed.
For 2026, the state pension pays £203.85 per week if you qualify for the full payment. Those who paid into SERPS may be eligible for up to an additional £204.68 per week if their contributions were maxed out. This includes both SERPS and S2P.
Can You Find an Additional Pension?
If you receive a standard pension but no additional pension, either from private sources or from the government under the additional state pension payments system, you may have an additional pension you have not claimed.
Many retirees who opted out of the SERPS pension, especially those who did so automatically through their employer and are unaware of it, may be entitled to more than they currently receive.
Fortunately, it’s relatively easy to locate these additional pensions. You can use a third-party service or the government’s official pension tracing service.
Alternatively, you can send a letter with your information, including your National Insurance number, to:
SARS/DPU
National Insurance Contributions & Employers Office
HM Revenue and Customs
BX9 1AN
Your letter should state that you want to track down any pensions the government knows about, including your SERPS pension. HMRC will respond within 30 days and give you the information they have.
Other options to track down your pension funds, including private pensions, include:
- Contacting previous employers if they still exist. These employers should have your employment records and information about your pension payments. Contact their HR departments with your query.
- Check old paperwork. If you still have old pay slips, pension scheme booklets, or correspondence, you may be able to identify where your pension contributions went. You may even find archived bank statements.
- Talk to your bank. They may be able to review old bank statements to identify old pension contributions and where they went. The recipient account name can help you identify the right person to contact to claim a lost pension.
- Contact old pension providers. You may remember the name of a pension provider and can ask them directly if you have a pension with them that you can claim.
Identifying any pensions you aren’t currently receiving is the first step in managing your finances in retirement.
Inheriting SERPS Pensions
Another consideration is whether you can inherit your spouse’s SERPS pension, or whether your spouse can inherit yours.
Unfortunately, the amount you can inherit depends on the deceased’s date of birth and gender.
To make this easier to visualise, here is this data in a table:
| Gender | Date of Birth | Inheritance Percentage |
|---|---|---|
| Men | 5 October 1937 or earlier | 100% |
| From 6 October 1937 to 5 October 1939 | 90% | |
| From 6 October 1939 to 5 October 1941 | 80% | |
| From 6 October 1941 to 5 October 1943 | 70% | |
| From 6 October 1943 to 5 October 1945 | 60% | |
| From 6 October 1945 onwards | 50% | |
| Women | 5 October 1942 or earlier | 100% |
| From 6 October 1942 to 5 October 1944 | 90% | |
| From 6 October 1944 to 5 October 1946 | 80% | |
| From 6 October 1946 to 5 October 1948 | 70% | |
| From 6 October 1948 to 5 July 1950 | 60% | |
| From 6 July 1950 onwards | 50% |
No matter what, you can always inherit 50% of SERPS pensions.
Cashing In a SERPS Pension
Another common question is whether you can “cash in” or receive your SERPS pension as a lump sum rather than an ongoing disbursement.
The simple answer is no; you cannot cash in your SERPS pension or additional state pension. It’s guaranteed for life, so you receive it for as long as you live.
However, if you opted out of SERPS at some point, the private pension you receive instead may have both limitations and the option to cash it in. This varies depending on the type of pension you receive.
Planning for the Future
Since your pension only lasts as long as you’re alive, and only your spouse can inherit any of it – and even then, usually only half of it – you may be looking for other ways to provide for your family after you’re gone.
For example, if your spouse has already passed away, your children don’t inherit your pension. Your savings and other investments can certainly be part of your estate, but is there more you can do?
The answer here is life insurance. While it can be potentially tricky to get life insurance when you’re over 50, there are still many options available, including guaranteed cover.
With life insurance, you pay a relatively small monthly fee for a much larger payout if you pass while you’re covered.
Those benefits can go to a spouse, but also to children, other family members or other beneficiaries of your choosing.
If you want to learn more about life insurance or pensions, our life insurance blog contains excellent resources and useful information. If you don’t find an answer there, feel free to reach out.
Our insurance experts are always happy to answer any questions and help you with the application process.
Speaking of applying, we make it easier than ever to get quotes from the country’s biggest and best insurance providers.
Fill out this form, and you’ll get quotes without the hassle of applying individually. This makes it easier to choose the best cover and protect your loved ones’ future.
Do recipients of the SERPS Pension commonly spend their income on life insurance?
To make it simple for loved ones, British seniors and over 70’s coverage are options people consider for their funeral and other costs when they die.
Offering families the benefit of a guaranteed lump sum payment just after death is a good plan for many people who are over 50, and as people get closer to 60 or 65, the issue potentially becomes more pressing.
One of the favourite insurance companies is Saga because of its stability and long track record.
Another household name is AXA, which offers very competitive terms.
Steve Case is a seasoned professional in the UK financial services industry, with over twenty years of experience. At Insurance Hero, Steve is known for simplifying complex insurance topics, making them accessible to a broad audience. His focus on clear, practical advice and customer service excellence has established him as a respected leader in the field.
