
What Is Private Health Insurance In The UK?
We are often asked: What is private health insurance? In basic terms, private health insurance (also known as private medical insurance or PMI) is financial protection that covers the cost of private health care if you become sick, helping you get better.
A private health insurance policy works alongside the NHS. It provides access to reduced waiting times, treatments that may only be available privately and a wider choice of clinics and hospitals.
As with other types of insurance, private health insurance involves paying a monthly premium to an insurer, who will then pay for private treatment covered under the policy’s terms.
The range of medical treatment available will depend on the type of policy and the premium you pay.
Get A Low-Cost Health Insurance Quote Today At A Price That Suits You

Is Private Health Insurance Worth It?
Is private health insurance worth it? Would you like to know what you can access?
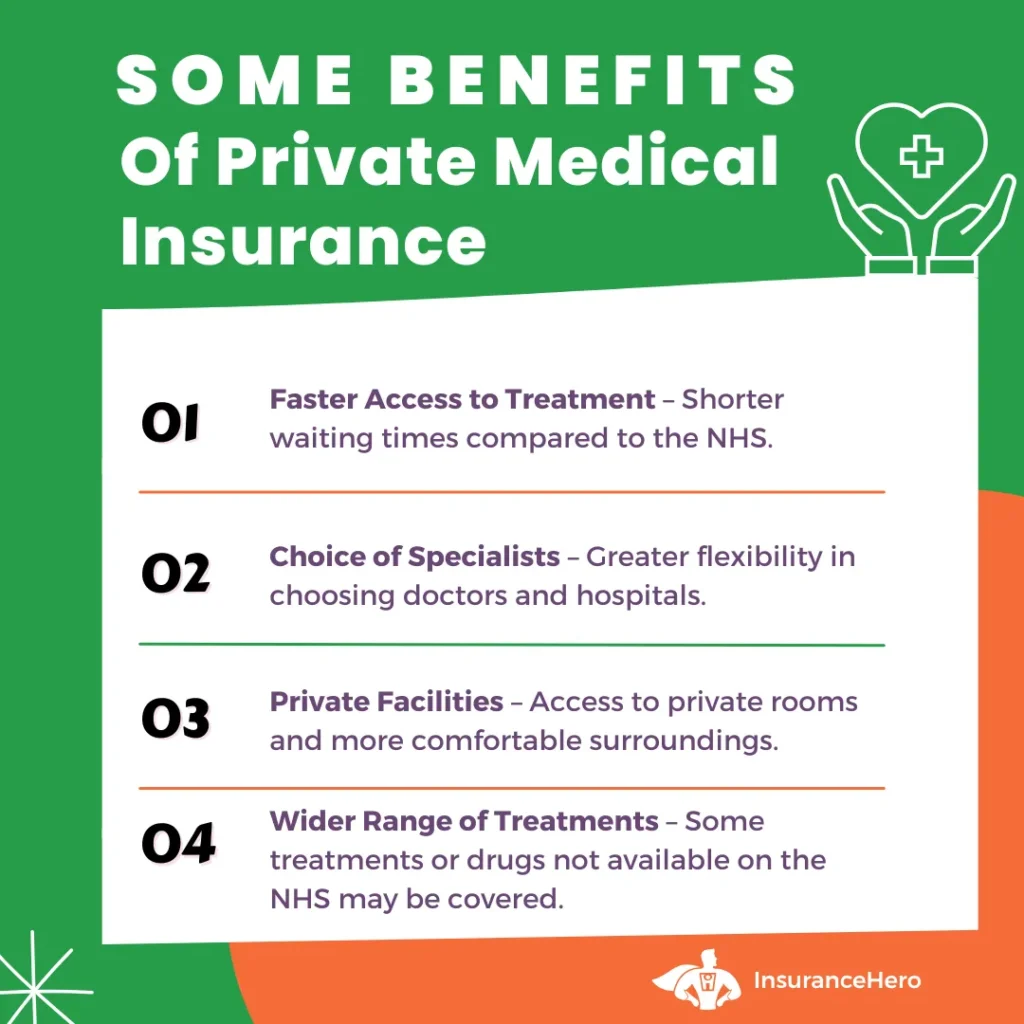
Here are 15 potential benefits of having a private medical insurance policy in place:
- Access to medicines and treatments that may not yet be available on the NHS.
- A broader selection of drugs and treatments that will never be available on the NHS due to high costs.
- Little or no waiting lists for consultations
- Little or no waiting lists for treatments
- Access to private hospitals with private rooms allows for greater relaxation.
- Access to private clinics and hospitals in greener, quieter areas.
- Higher standards of cleanliness reduce the risk of infection, including MRSI.
- Consultant-led private medical care and entitlement to second opinions from medical experts.
- A superior and broader choice of food and drink.
- More flexible visiting hours compared to NHS hospitals.
- Private hospital staff often receive training to spend more time providing for people’s needs.
- A longer discharge time allows for better recovery, with medical professionals present.
- Free access to satellite TV and radio.
- No parking costs.
- Private medical insurance (PMI) can cost less than your council tax bill.
Is There One Compelling Reason for Getting Private Health Insurance?
The NHS provides an excellent service and has been extensively praised and appreciated by the public following the Coronavirus pandemic.
Unfortunately, it has now become increasingly stretched as COVID-19 priorities have led to NHS waiting lists for investigative work, such as biopsies, blood tests, scans, and X-rays, often resulting in some patients’ conditions worsening.
Routine operations have also been delayed or suspended as the NHS has struggled to control the pandemic. It will be some time before the NHS can operate at standard levels and timescales.
A recent analysis undertaken by the BMA estimates that the number of patients in the UK waiting over a year for medical treatment exceeds 436,000, the highest level since August 2007.
If you become unwell and rely on an NHS hospital, waiting times can be substantial, meaning you may be inconvenienced for a long time.
Is private health insurance worth it? The uncertainty around the NHS strengthens the case for private medical insurance to access priority treatment, and depending on the policy you choose, the cost may be lower than you think.

Private Health Insurance – Three Important Considerations
Three essential considerations must be taken into account before deciding whether private health insurance is worth having in the UK, and we will run through these now.
1. Does the NHS cover all your requirements?
Did you know you will still need to use the NHS for Accident and Emergency and GP services? There is also no guarantee you will receive faster treatment for serious illnesses with a private policy than by using the NHS directly.
The NHS may cover your basic needs, but private health insurance can help treat acute conditions.
These are sudden conditions with a limited treatment term. They differ from chronic conditions, like diabetes, that you may have to live with.
For acute conditions, you can see a specialist, enjoy short or no waiting times, and choose from a wide range of clinics and hospitals.
2. Do you already have health coverage through your employer?
It may be helpful to check if you or your family members already have access to private medical insurance through an employer, which you may have overlooked.
Even if no policy is available, it may be worth asking whether your employer is willing to implement a scheme for you and your colleagues.
Purchasing a policy for multiple staff members can help reduce costs.
Even if you are leaving an employer, ask the insurer who runs the firm’s scheme about any continuation options.
This may allow you to maintain higher-quality private medical insurance cover at a lower premium.
3 Self-Insuring Options
Self-insuring means setting aside money in your emergency fund for medical expenses.
You don’t need insurance to receive private healthcare treatment, and you can choose to pay the bills yourself. If you do not spend your fund, no money ebbs away, unlike premiums in a policy you never claim.
The downside is that it takes longer to build a fund than the instant cover you get from paying monthly premiums into a policy.
Additionally, treatments and medical procedures can be hugely expensive, with a knee or hip replacement starting at £10,000 privately.
I Want to Move Forward and Take Out a Policy – What Are the Next Steps
Suppose you answer yes to private health insurance and decide to proceed with a policy. In that case, you need to understand the available private cover options, the key features of a policy, the factors affecting cost, and how to implement a policy.
We will cover these in detail now.
What does private health insurance cover?
First, ask why you need private health insurance. Is it to cover every eventuality or for specific medical conditions?
Private medical insurance offers three types of coverage, and you should choose one that closely matches your circumstances.
Basic private health insurance
Basic cover will provide basic inpatient care at a private clinic or hospital. Inpatient treatment is the use of a hospital bed or an overnight hospital stay.
It also offers day-patient treatment, where a bed is required for a single day.
Medium-level private health Insurance
Medium-level healthcare insurance cover provides all the benefits of basic insurance. It also includes outpatient care (no overnight stay required), consultation appointments, physiotherapy, psychiatric services, and diagnostic tests.
Comprehensive private health insurance
Comprehensive private insurance covers all basic and medium private care services, including outpatient treatment and additional services such as private ambulance, home nursing, and alternative medicine.
As with other types of insurance plans, comprehensive cover typically includes add-ons that allow a policy to be tailored to a particular situation.
10 companies offering private health insurance in the UK
- Bupa
- AXA Health
- Aviva
- Vitality
- WPA (Western Provident Association)
- The Exeter
- Freedom Health Insurance
- General & Medical Healthcare
- CS Healthcare (now part of Bupa)
- National Friendly
What are the disadvantages of private health insurance?
Private healthcare insurance does not cover all conditions and treatments, which include the following:
- Emergency hospital treatment is covered by the NHS
- Travel insurance will be required to cover overseas treatment.
- Elective treatment is not covered; it is a treatment you want but do not need.
- Lifestyle treatment, such as rehabilitation, may be triggered by drink or drug abuse.
- Chronic conditions are ongoing treatments for incurable diseases like diabetes or HIV.
- Pregnancy care is not generally covered by private medical insurance.
- Any pre-existing medical conditions are not covered.
What should I know before considering a private medical insurance policy?
Suppose you have made a favourable decision regarding private health insurance and now wish to move forward with private cover.
In that case, there are certain parts of a policy that you need to be aware of, and these include the following:
Excess considerations
Selecting a higher excess (you pay a specified amount towards a claim) can significantly lower private health insurance costs and make any claims more costly.
Consider whether you want to cover everything or just a one-off, expensive medical problem, such as a hip replacement.
Understanding any exclusions or restrictions
Beyond pre-existing conditions, you may also be unable to claim in other situations, such as pregnancy or cosmetic surgery.
Checking what is covered on a policy before you sign up is vital to avoid unpleasant surprises.
Add-on extras
You can tailor a policy and pay only for the services you need. For example, you may decide that other cancer treatments or enhanced outpatient treatments would be desirable in the future.
Carefully consider why you need health insurance and tailor the policy accordingly.
Understanding the private medical insurance claims process
If you need to make a claim, it’s essential to understand the claims process and timeframes, as these vary by policy.
A typical claims process will be:
- Referral from your GP
- Register the claim with your insurance provider
- Your provider will check if you are covered for the claim
- If covered, your GP will refer you to a private clinic or hospital
How Much Does Health Insurance Cost?
Many factors affect the cost of health insurance, making like-for-like comparisons difficult.
It depends on the insurance company and includes the following:
- Medical history—Private insurance does not cover pre-existing conditions. If you have existing medical conditions, they indicate a risk of future problems.
- Your lifestyle—how you live, such as your weight, smoking, drinking, and the amount of exercise you undertake —will all affect private health insurance premiums.
- Family history—Does your family have a history of any specific health problems? A history of these problems may indicate that you are at risk of the disease and may increase your insurance costs.
- How old are you? Your age will directly affect the cost of your cover, as older age typically increases the likelihood you will claim, making it more expensive.
- Who is the cover for? Health insurance policies are flexible and can cover individuals, families, or couples. It can be cheaper to have a sole policy rather than several different policies.
- Where do you live? Unfortunately, certain parts of the UK are associated with certain medical conditions; therefore, your postcode can affect the cost of insurance coverage.
How can I reduce the cost of private health insurance?
[/pullquote]There are several ways to help reduce the cost of private health insurance, and these include the following:[/pullquote]
- Limiting the hospitals and clinics available to you will reduce your cover cost.
- Choosing a higher excess when you make a claim will lower your insurance premiums.
- Adding a waiting period means you must use NHS treatment if the waiting time is under six weeks. After more than six weeks, you can claim on your insurance and receive private treatment.
- A no-claims discount, like with car insurance, may help you get a discount if you haven’t claimed on your health insurance for a long time.
- If you live in a healthy postcode, private healthcare providers may offer lower premiums than in other places.
I Am A UK Resident – How Can I Buy Private Health Insurance?
Once you have decided whether private health insurance is worth it in the UK, it is vital to ensure any policy closely matches your circumstances.
As mentioned, comparing plans on a like-for-like basis can be complex and involves many variables. To get a rough idea of whether health insurance will be affordable for you, research the approximate cost of basic, medium, or comprehensive insurance by comparing plans.
Next, contact Insurance Hero for an accurate quote. We will carefully review your requirements and ask questions to ensure that any policy quote aligns closely with your needs.
Further reading and external resources:
- https://www.bupa.co.uk
- https://www.bma.org.uk/media/1831/bma-guidance-for-patients-wishing-to-buy-private-medical-insurance-sept-19.pdf
- https://www.moneyhelper.org.uk/en/everyday-money/insurance/do-you-need-private-medical-insurance
- https://www.imperial.ac.uk/human-resources/benefits/live-well-work-well/bupa-eduhealth/

Steve Case is a seasoned professional in the UK financial services industry, with over twenty years of experience. At Insurance Hero, Steve is known for simplifying complex insurance topics, making them accessible to a broad audience. His focus on clear, practical advice and customer service excellence has established him as a respected leader in the field.
